by Chris Williams | Oct 21, 2026 | Blog
The honest answer: three to four weeks from the day the seller delivers complete data for a full-scope quality of earnings analysis on a typical lower-middle-market deal, and inside ten business days for a QoE Lite. Not the two days some software-first services advertise, and not the six to eight weeks a backlogged firm will quietly consume.
The more important point is the phrase most providers skip: from the day the seller delivers complete data. The QoE clock does not start when you sign the engagement letter. It starts when the data shows up, and that distinction is where deal timelines actually live or die. I have been through this three times as a buyer, always with an exclusivity window burning, so let me walk through what really drives QoE duration and how to compress it.
The honest range
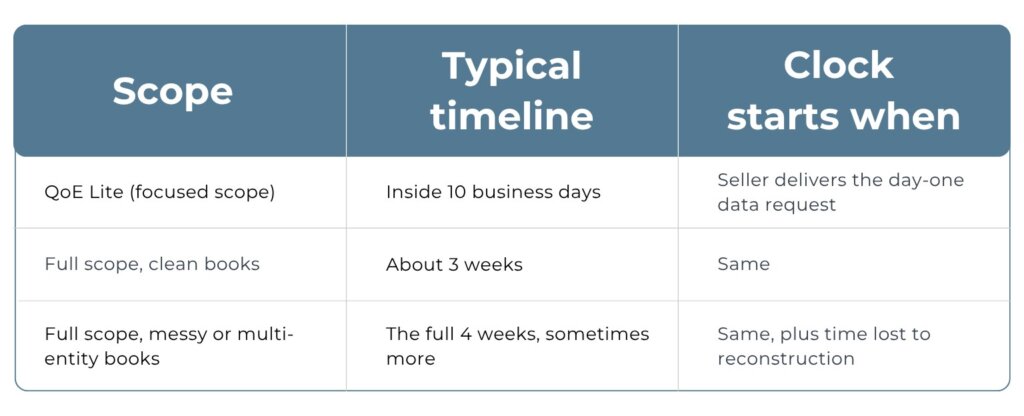
Be suspicious of both tails. A QoE promised in 48 hours is a template, not an analysis; nobody proves cash in two days. And a provider quoting six-plus weeks because of staffing backlog is not describing the work, they are describing their capacity problem, and paying for it with your deal clock.
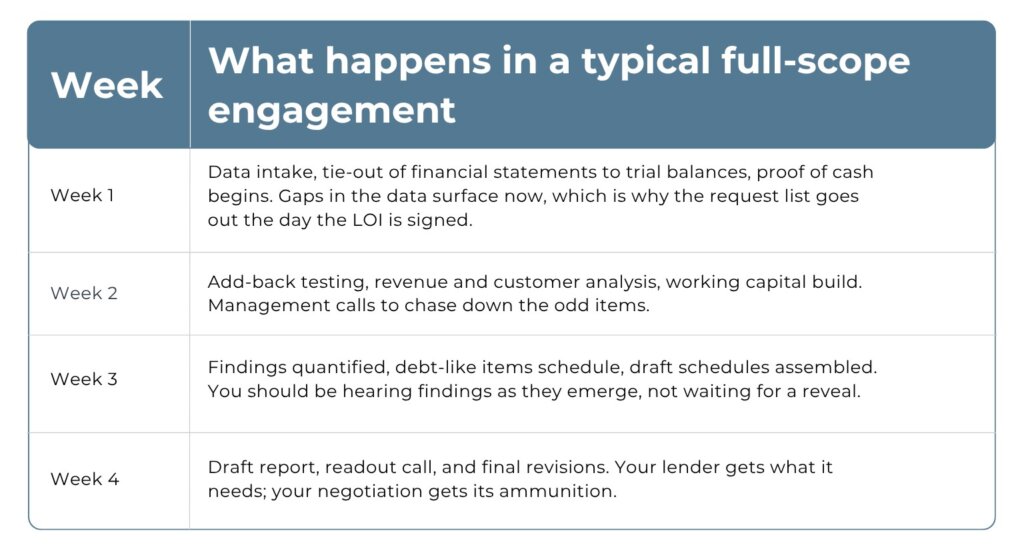
What a full-scope engagement actually looks like, week by week
The three things that drive where you land
Data readiness. The single biggest variable, and it belongs to the seller. A seller who takes three weeks to produce bank statements adds three weeks to your timeline, full stop. Get the day-one request list to the seller the day the LOI is signed, and keep it lean: request only the most important things. Don’t kill the deal immediately with a massive, overwhelming diligence list. A focused list gets answered in days; a 200-line data dump request gets answered never.
The state of the books. Clean accrual books in QuickBooks Online move fast. Cash-basis books with commingled personal expenses and an inventory number nobody believes move slower, because the team is reconstructing reality before it can analyze anything. If you already know the books are rough, budget for the top of the range and scope accordingly.
Scope. QoE Lite lands inside ten business days because it concentrates on the kill-shot questions. Full scope takes the extra weeks because the working capital build, the debt-like items schedule, and dollar-quantified findings are real analytical work. Our QoE Lite vs. full-scope guide covers which one your deal needs.
Where the QoE sits in your deal clock
Most LOIs grant 60–90 days of exclusivity, and the QoE sits at the front of the queue: financing commitment, legal diligence, and purchase agreement drafting all wait on its findings. A four-week QoE inside a 60-day window leaves your lender and your lawyer half the clock. A six-week one leaves them scraps and hands the seller leverage as the expiration date approaches.
That is why the question to ask a provider is not just how long, but when can you start. A fast team that cannot start for a month is slower than a steady one that starts Monday. Ask for both numbers in writing: start date and duration. A firm that will not commit to either is reserving the right to consume your window.
How to compress the timeline (without cutting corners)
Four moves, all cheap. Send the data request the day the LOI is signed, not the day the engagement letter is countersigned. Keep the request list short and important. Ask the seller to grant read-only access to the accounting system, which eliminates the export-and-email shuffle entirely. And pick a provider that surfaces findings as they emerge, so your lender, your lawyer, and your negotiation are moving in parallel with the analysis instead of waiting for a final PDF.
That last one is a scoping question worth asking directly: will I hear findings weekly, or at the end? The difference is not comfort; it is calendar. A finding you learn in week one is a term you renegotiate in week two. A finding you learn in week four is an extension request.
Frequently asked questions
How long does a QoE take?
Three to four weeks from receipt of complete data for a full-scope analysis on a typical lower-middle-market deal; inside ten business days for a QoE Lite. Seller responsiveness is the biggest variable.
What is the fastest a QoE can be done?
A QoE Lite on clean books with a responsive seller can land in under two weeks. Anything promised in a day or two is a template review, not a quality of earnings analysis; there is no way to prove cash that fast.
What delays a QoE most often?
Slow seller data delivery, followed by messy books that need reconstruction before analysis. Both are partly manageable: send a lean request list at LOI signing and budget extra time if you know the books are rough.
When should I order the QoE?
Immediately after signing the LOI. The engagement can be scoped during LOI negotiation so the data request goes out on day one of exclusivity, which protects the back half of your window for financing and legal.
Know your start date before you sign the LOI
If you are negotiating an LOI now, the highest-leverage call you can make is the one that locks a diligence start date. Send us the CIM or the seller’s P&L and a partner will come back with scope, a fixed fee, and the earliest start, usually within a day. Your exclusivity window is the scarcest asset in the deal; we scope around it.
Get a fixed-fee QoE quote from System Six.
by Chris Williams | Oct 18, 2026 | Blog
Every buyer heading into diligence faces the same scoping decision, usually with an exclusivity clock already running: how much quality of earnings work does this deal actually need? Buy too little and you close on numbers nobody tested. Buy too much and you burn five figures and three weeks on schedules your deal never required.
The industry’s name for the smaller product is a red-flag QoE. We call ours QoE Lite, because the name describes what it is: the same rigor, concentrated on the questions that kill deals, without the full analytical build-out. Having bought three companies myself, I have used both scopes, and the right answer is almost always obvious once you look at the deal honestly. Here is how to look.
What a QoE Lite covers
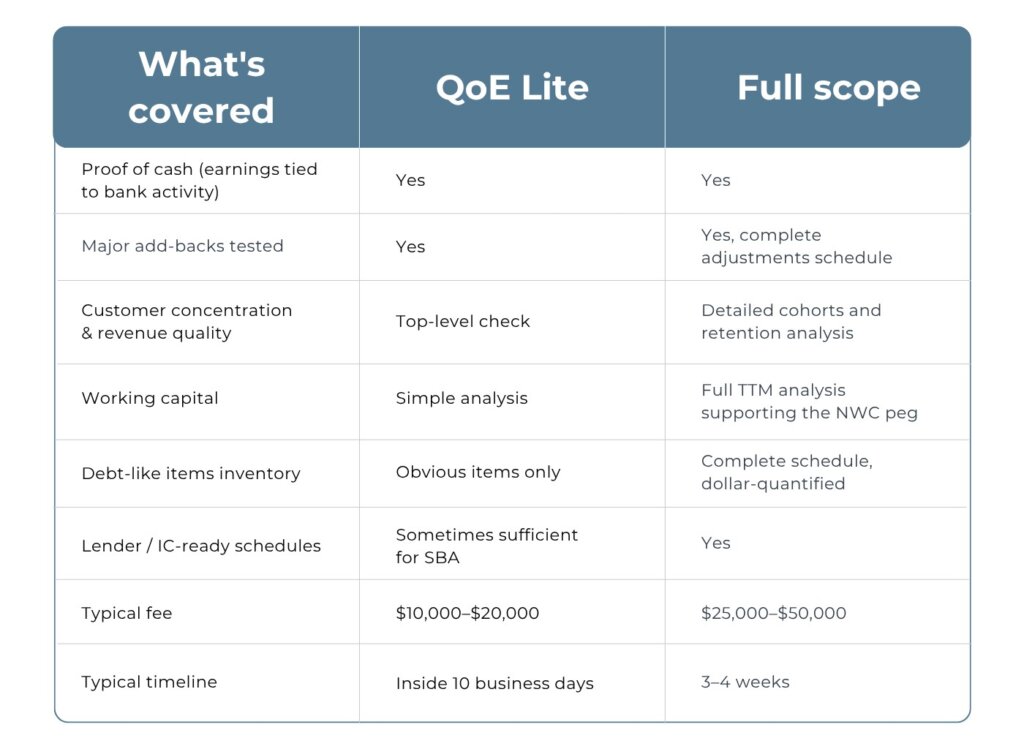
QoE Lite concentrates on the kill-shot questions. Does cash tie out, meaning can reported earnings actually be traced to bank activity? Are the major add-backs real, or does adjusted EBITDA collapse under the replacement test? Is there a customer concentration or revenue-quality problem severe enough to walk away from? And what does a simple working capital analysis say about the cash the business actually needs to run?
That last item matters more than most buyers expect. Even a Lite engagement should tell you enough about working capital to avoid the post-close cash crunch that quietly wrecks buyers who did everything else right.
What QoE Lite deliberately skips: the complete debt-like items schedule, detailed revenue cohorts, the full trailing-twelve-month working capital build that supports a negotiated NWC peg, and dollar-quantification of every secondary finding. Those omissions are the price of speed and the lower fee, and on many smaller deals they are omissions you can live with.
What full scope adds
Full scope is the complete anatomy: the line-by-line EBITDA bridge, revenue cohorts and retention, the working capital analysis that sets a defensible peg, a dollar-quantified debt-like items inventory, and findings packaged so a lender’s credit committee or an investment committee can rely on them without re-work.
The practical difference shows up in negotiation. QoE Lite tells you whether to proceed. Full scope arms you to reprice: every finding sized in dollars, every schedule ready to hand across the table when the seller’s accountant pushes back. If diligence is going to move price or terms, full scope is what moves them.
Side by side
Which one your deal needs
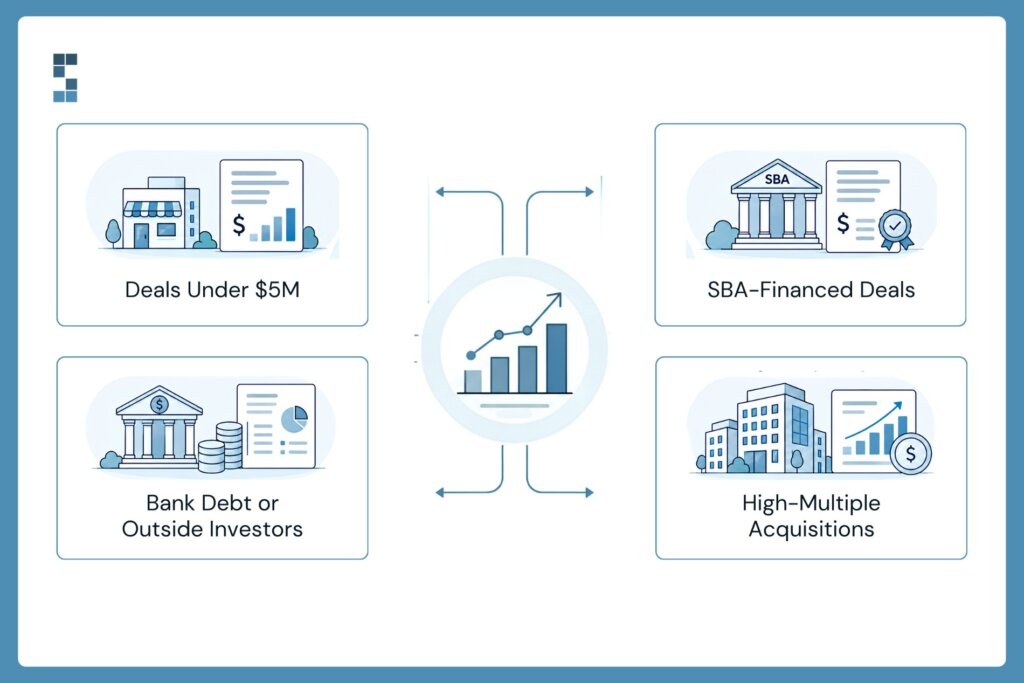
Deals under $5M: start with QoE Lite. At this size the books are usually simple enough that the kill-shot questions are most of the risk, and QoE Lite will work well for many deals. The exception is complexity out of proportion to size: multiple entities, deferred revenue, or heavy inventory push you toward full scope even on a small deal.
SBA-financed deals: often QoE Lite, confirm with your lender. Many SBA lenders accept a focused-scope report from a credible independent provider. Ask your lender what they require before you scope; it is a five-minute call that can save you $20,000.
Bank debt outside SBA, or outside capital: full scope is often where you will need to be. Senior lenders, private credit, and equity co-investors expect the complete schedules, and independent sponsors raising deal-by-deal need a report that travels to family offices. The trust-instrument job requires the full product.
Paying above a small-deal multiple: full scope. At 4–7x, every dollar of EBITDA that fails scrutiny is four to seven dollars of price. The bigger the multiple, the more expensive it is to skip the analysis that tests the number.
The upgrade path: the best of both
The pattern I recommend for cost-conscious buyers: start QoE Lite, with a pre-agreed upgrade path to full scope if the deal survives the first pass and is large enough to warrant it. If the Lite work surfaces a deal-killer, you spent $10,000–$20,000 to avoid a seven-figure mistake. If it comes back clean and the deal justifies it, you upgrade.
Good providers structure the engagement this way and credit the QoE Lite fee against the full-scope engagement, so the staged approach costs nothing extra. We scope this way deliberately. It puts the diligence spend where the deal risk actually is, and it means nobody pays for analysis their deal does not need.
Frequently asked questions
What is a red-flag quality of earnings?
A focused-scope QoE, which we call QoE Lite, concentrating on proof of cash, major add-backs, obvious risks, and a simple working capital analysis. It typically runs $10,000–$20,000 and lands inside ten business days.
Is QoE Lite enough for an SBA loan?
Often, yes. Many SBA lenders accept a focused-scope report from an independent provider, but requirements vary by lender. Confirm what yours requires before scoping the engagement.
Can I upgrade from QoE Lite to full scope mid-diligence?
Yes, and you should agree on the upgrade path before engaging. A good provider credits the Lite fee against full scope, so staging the work costs nothing extra.
What does each scope cost?
QoE Lite runs $10,000–$20,000 for deals under $5M. Full scope from a boutique firm runs $25,000–$50,000 for typical lower-middle-market deals. See our full pricing guide for what drives the ranges.
Scope it in one call
Send us the CIM or the seller’s P&L and a partner will tell you which scope your deal actually needs, as a fixed fee with a start date. If QoE Lite is the honest answer, that is what we will quote.
Get a fixed-fee QoE quote from System Six.
by Chris Williams | Oct 6, 2026 | Blog
The short answer
Only if you were going to buy it anyway. A deduction returns your marginal tax rate, not the full purchase price, so spending money you didn’t need to spend still leaves you poorer. Where year-end spending does pay off is timing: pulling a purchase you’d make in the new year into December. And some of the best year-end moves don’t involve buying anything at all.
Picture Joel on December 28th. He runs a small marketing agency, and he’s standing in a computer store with a cart full of gear: two new monitors, a laptop he’ll probably give to an intern, a standing desk still in the box. Somebody told him he should “spend some money for taxes.” So here he is.
I get it. Nobody likes writing a check to the IRS, and buying something feels better than paying a bill. But before you load up the cart, let’s do the math most people skip.
What’s the math people skip?
A deduction doesn’t give you back what you spent. It gives you back your marginal tax rate on what you spent. That’s it.
Say your combined federal and state rate is roughly 30%. You spend $10,000 on things you didn’t need. The deduction saves you about $3,000 in tax. So you’re about $7,000 worse off than if you’d done nothing. Plus you own a standing desk you didn’t want.
Put another way: you just spent a dollar to save thirty cents. Would you do that anywhere else in your business?
That’s why the honest answer to “Should I spend money to save taxes?” is almost always no. Spending to save taxes is like paying for a meal you’re not hungry for because the restaurant offered a discount. The discount is real. The meal still costs you.
Where does year-end spending actually work?
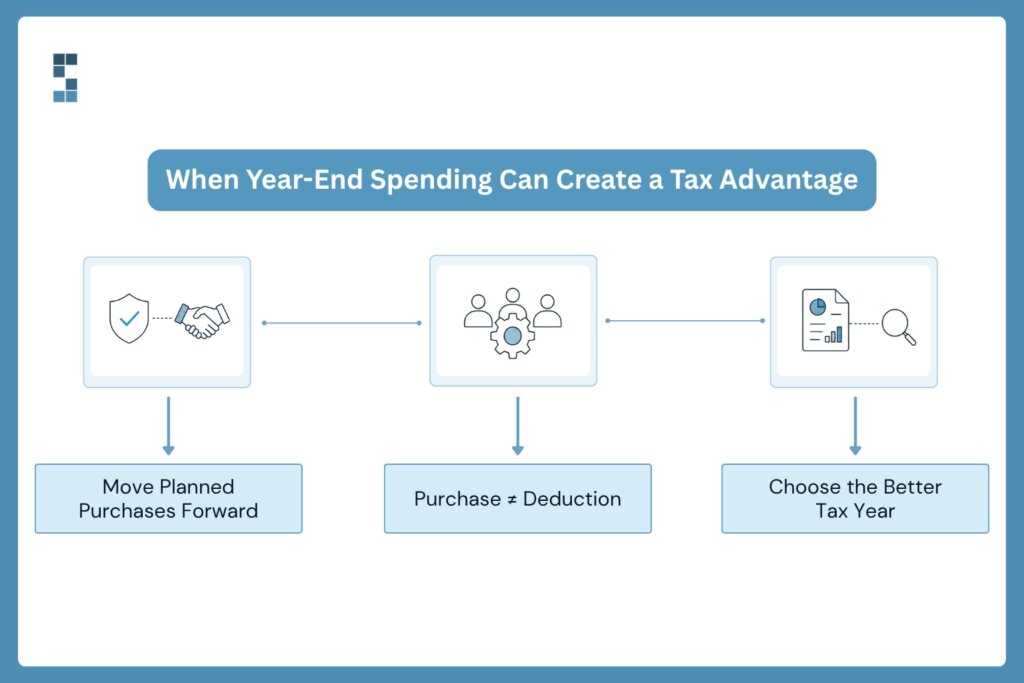
Timing. That’s where the real money is.
If a purchase is already on next year’s list, and you’d buy it in February no matter what, pulling it into December can move the deduction a full year earlier. You were spending the money either way. Now you get the tax benefit twelve months sooner, which means more cash in your pocket while you need it.
What kinds of purchases? Equipment you’ve already planned to replace: the aging laptops, the server, the furniture for the new hire starting in January. Software or subscriptions you’d renew anyway, prepaid within the allowed window. For a cash-basis business, that generally means the benefit doesn’t run past twelve months or the end of next year, whichever comes first. And everyday supplies you burn through on a predictable schedule.
There are a few catches. Equipment usually has to be placed in service by December 31, not just ordered or paid for. A laptop sitting in a warehouse doesn’t count. Whether you can deduct the full cost this year depends on the rules for immediate expensing, called Section 179 and bonus depreciation, and those limits have changed more than once lately. Your accounting method matters, too. If you’re on the accrual basis, paying in December doesn’t automatically pull the deduction forward the way it does on a cash basis. So confirm the current limits and how they apply to you with a tax professional before you buy.
One more wrinkle worth knowing. If you expect next year to be a much bigger year, a deduction might be worth more next year than this one. Pulling it forward isn’t automatically a win. It’s a judgment call, and it’s worth making on purpose.
What else can you do that doesn’t involve buying things?
Quite a lot, actually. These are often the better moves.
The first is timing invoices and collections. If you file on a cash basis, income counts when you receive it. Sending a few invoices on January 2nd instead of December 20th can shift that income into next year. There’s a limit, though. If a client hands you a check in December, you can’t just leave it in a drawer and call it January income. The IRS treats money you could have collected as received.
The second is retirement contributions. A contribution to a retirement plan can lower your taxable income without buying anything you don’t need, and the money stays yours. Deadlines differ by plan type. Some plans need to be in place before year-end for certain contributions, while others can be set up and funded later. That’s exactly why you want to ask early.
The third is paying bonuses on time. A cash-basis business deducts bonuses in the year it pays them, so a bonus run in December lands this year and one in January lands next year. Accrual-basis businesses can sometimes deduct bonuses earned this year if they pay them within two and a half months after year-end, though the rules differ for owners and their families. Either way, payroll has to actually run, and that takes planning.
Why does this conversation belong in early November?
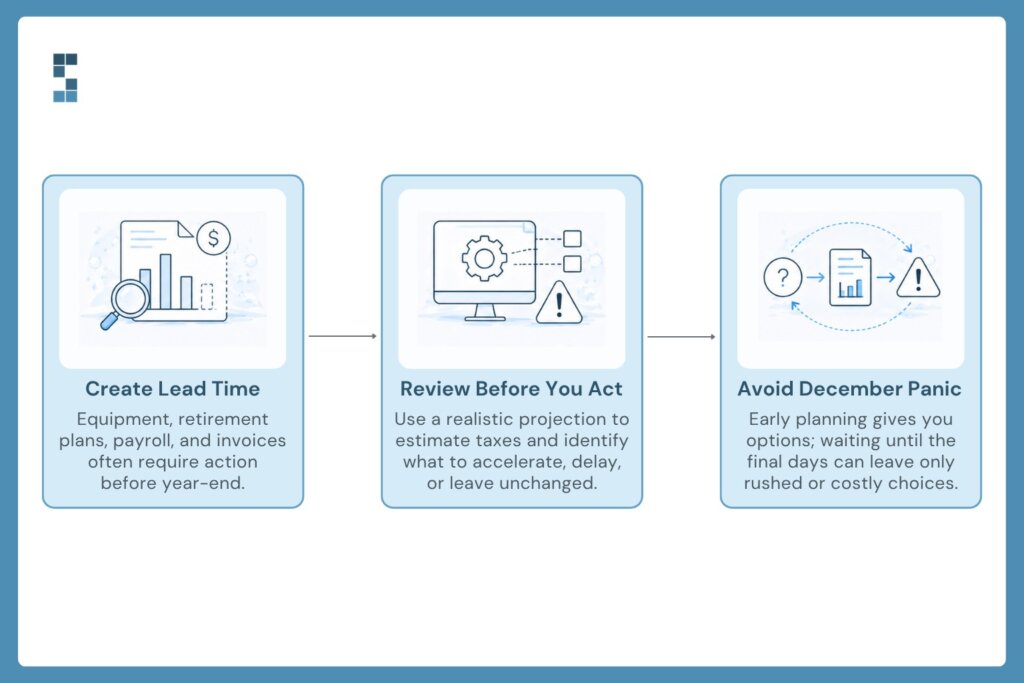
Because by December 30th, the only options left are the bad ones.
Think about everything above. Equipment has to be ordered, delivered and set up. Retirement plans may need paperwork. Bonuses need a payroll run. Invoices need a decision before they go out. Every good move takes a little lead time. The one move that doesn’t is the cart full of things you didn’t need.
Early November gives you room. You can look at a realistic projection of the year, see roughly what you’ll owe, and decide what’s worth pulling forward, pushing back or leaving alone. That’s a calm conversation. The December 28th version is a panicked one.
This is where a good partner earns their keep. One of our clients, Aiko, described it as having a team that’s “open to questions and equipped with a lot of recommendations.” That’s what year-end planning should feel like. Not a scramble. A short list of good choices, made on purpose.
Spend on purpose, not for a deduction
Here’s the rule I’d tape to the wall: if you’d buy it anyway, consider buying it sooner. If you wouldn’t, keep your money. A tax deduction is a discount, not a reason to shop.
If you’d like to walk through your own year before the options narrow, we’ll set up a year-end planning call. You can start here: systemsix.com/get-started.
Frequently asked questions
Does a $10,000 business purchase reduce my taxes by $10,000?
No. It reduces your taxable income by up to $10,000, which cuts your tax by roughly your marginal rate. At a combined 30%, that’s about $3,000.
Can I deduct equipment I order in December but receive in January?
Generally not for this year. Equipment usually has to be placed in service, meaning ready and available for use, by December 31. Confirm the details with your tax professional.
Does prepaying next year’s expenses help on an accrual basis?
Usually much less than on a cash basis, because accrual-basis businesses deduct expenses when they’re incurred, not simply when they’re paid. Your preparer can tell you which method you use and what applies.
This post offers general information for US businesses filing on a calendar year. It isn’t tax advice, and your situation may differ. Verify all limits and rules, including Section 179, bonus depreciation, prepaid expense and retirement plan deadlines, against current IRS guidance before acting.
by Chris Williams | Oct 2, 2026 | Blog
The short answer
When money you take out of the business as an owner gets recorded as an expense, your profit and loss statement shows the business earning less than it really does. Day to day, nobody notices. But the moment a lender, a buyer or an investor relies on those numbers, the understatement shrinks your loan, your valuation and your credibility. Finding it takes about five minutes. Fixing it now is far easier than fixing it in the middle of a deal.
I spent years in private equity reading quality-of-earnings reports. Hundreds of pages, most of them dull, written by accountants whose whole job is to figure out what a business really earns. And one finding showed up so often I could almost predict it: the owner’s own money was sitting in the expense accounts.
It never looked dramatic. A line called “Consulting — G. Ruiz.” A “Misc” account with a suspiciously steady $10,000 a month. Small things. But small things in the wrong account have a way of turning up at the worst possible moment.
Let me show you why, and how to check your own books before anyone else does.
Why does this happen?
Picture the end of the month. Your bookkeeper is working through the bank feed, and there’s a $10,000 transfer to your personal checking account. Money left the business. Something has to be coded. The software wants a category, and “expense” is the easiest box to tick. It’s the path of least resistance, so it wins.
Nobody’s hiding anything. Often the bookkeeper simply wasn’t told what the transfer was, or the chart of accounts never had an owner’s equity account set up in the first place. Personal charges on the company card get the same treatment — your kid’s tuition lands in “Office expense” because there was nowhere else to put it.
And because the money really did leave, the bank balance still reconciles. The books look clean. They’re just wrong.
What does it cost you?
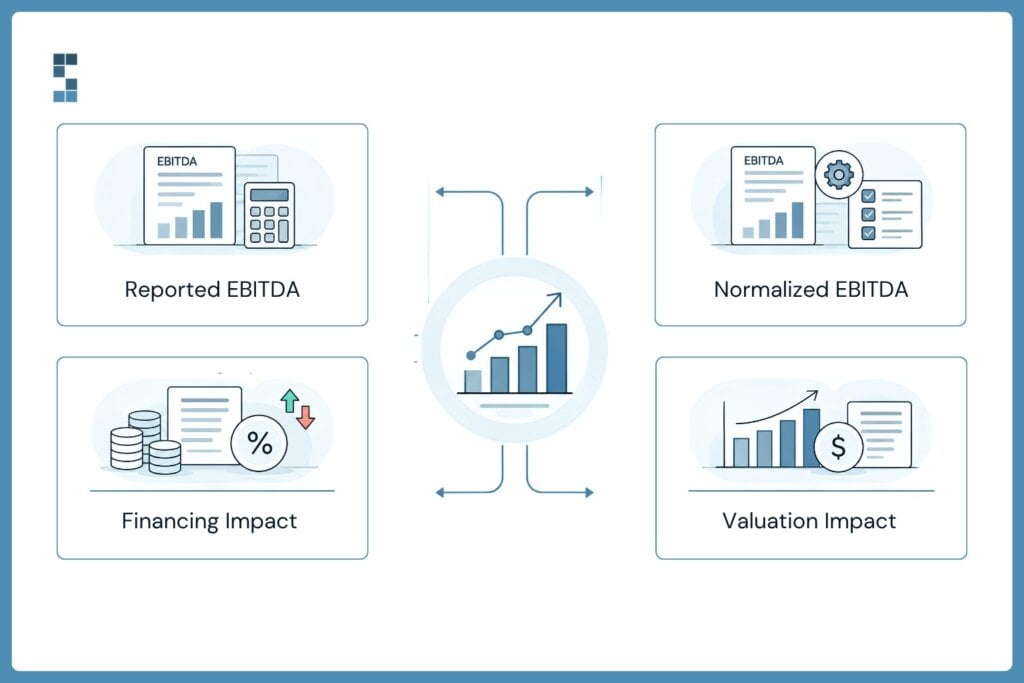
Here’s the part that surprises owners: on a normal Tuesday, it costs almost nothing. Your cash is your cash, wherever it’s coded. (It can create a tax problem, since a draw isn’t deductible, so it’s worth raising with your CPA.) The real cost arrives when someone outside the business has to trust your P&L.
Let’s use round numbers. Gabe runs a $2 million engineering consulting firm. His P&L shows $200,000 of EBITDA (earnings before interest, taxes, depreciation and amortization, a common stand-in for operating profit). Buried in his expenses is $120,000 he took home as draws over the year. His real EBITDA is $320,000.
Now watch what happens.
A lender sizing a loan at three times EBITDA offers him $600,000 instead of $960,000. A buyer paying four times earnings starts at $800,000 instead of $1.28 million — a $480,000 gap, before anyone negotiates a thing. To be fair, a buyer will also subtract what it would cost to pay someone to do Gabe’s job, so the true figure lands somewhere in between. But that conversation starts from his real numbers, not from a mistake. And a bank calculating debt-service coverage, with $160,000 of annual payments on the table, sees 1.25 times coverage on his reported numbers, right on the line many lenders draw. On his real numbers it’s 2.0 times, a comfortable yes.
Same business. Same clients. Same people. A very different answer.
How do you check your books in five minutes?
Open your trailing-12-month P&L. Scan the expense accounts and look for anything that reads like a person rather than a vendor. A name. An account called “Misc” or “Reimbursement.” One large, round number that shows up every single month, like clockwork. Vendors send invoices with odd amounts. Owners transfer round ones.
Then flip to the balance sheet. Look in the equity section for an owner’s draw or distribution account. Does it have real activity — a balance that grows across the year? If there’s nothing there, but you know money has clearly been leaving the business for your benefit, the draws are in the wrong place. That’s the tell.
That’s it. Five minutes, maybe ten if you pour a coffee first.
How do you fix it?
Start by reclassifying the draws. Your bookkeeper pulls the transactions out of the expense accounts and moves them to equity, month by month, with a short note on each. Go back at least as far as the period a lender or buyer will review, usually the last two or three years.
Next, set up the right equity accounts for your entity type, because the label matters. If you’re a sole proprietor or a single-member LLC, you’ll use an owner’s draw account that rolls into owner’s equity at year-end. In a multi-member LLC taxed as a partnership, each member gets their own draw and capital account. One wrinkle: guaranteed payments to partners for their work are deductible, so not every payment to a partner is a draw. If you’re an S corporation, your pay for working in the business runs through payroll as a reasonable W-2 salary, and that is an expense. Anything you take above it is a shareholder distribution, recorded in equity.
Finally, ask your bookkeeper to keep it clean going forward. A simple rule works: every transfer to an owner gets coded to equity unless someone documents a business reason. When we clean up a client’s books, this is usually one of the first changes. One of them, Trevor, put the result simply: “We are in a much better place today than we were twelve months ago.” That’s what this fix buys you. Not drama. Just numbers you can stand behind.
Why is it harder to untangle mid-deal?
Because a deal changes who’s asking and how much time you have.
In private equity, I watched diligence teams turn over every account in the general ledger. When they found owner spending in the expense lines, they didn’t just take the seller’s word for it. Each item had to be proven with bank statements, receipts and an explanation, often for three years at once, on a deadline, while the owner was also trying to run the company. Anything they couldn’t verify, they left out. And once a buyer finds one miscoded account, they start wondering about the others. The questions multiply. The timeline stretches. Sometimes the price gets renegotiated.
I saw it from the other side, too. When I bought System Six with an SBA loan, the bank underwrote the deal from the seller’s financials, line by line. Clean books made that process faster and calmer for everyone.
Here’s the thing: the work to fix this is identical whether you do it now or during diligence. Now, you do it calmly, on your own schedule, with no one watching. During a deal, you do it under a microscope with money on the line. Which would you rather?
If you’re thinking about a sale or an investment, our guide to quality-of-earnings reports walks through what a diligence team will look for. And if you’d like us to run the five-minute check with you and tell you what we find, we’re happy to: systemsix.com/get-started.
Frequently asked questions
Are owner draws a deductible business expense?
No. A draw or distribution is the owner taking money out of the business, not a cost of running it. W-2 salary paid to an S corporation owner through payroll and guaranteed payments to partners are treated differently, so ask your CPA how your entity type applies.
Is it called a draw or a distribution?
It depends on your entity. Sole proprietors and LLC members typically take draws. S corporation shareholders take distributions. Either way, it belongs in the equity section of the balance sheet, not on the P&L.
If I reclassify past draws, do I need to amend old tax returns?
Possibly, if the change affects the taxable income on a return you’ve already filed. That’s a question for your tax preparer, and it’s another reason to catch the problem early.
This post offers general information for owners of US small businesses. It isn’t tax or legal advice, and the right treatment depends on your entity type and circumstances. Talk with your CPA or attorney before making changes to your books or filed returns.
by Chris Williams | Sep 28, 2026 | Blog
The short answer
Three federal dates matter to calendar-year service businesses this quarter. October 15 is the final deadline for extended 1040 and calendar-year 1120 returns, and there’s no second extension. November 2 is the deadline for your Q3 Form 941 (October 31 falls on a Saturday), or November 10 if you made every deposit on time and in full. January 15, 2027 is the fourth-quarter estimated tax payment, and the decisions that set its size happen between now and December 31. State and local deadlines run on their own calendars, so check yours.
Every fall I get some version of the same phone call. The owner sounds calm, but they’re talking a little too fast. Their CPA just emailed. Something’s missing. The return is due in eight days.
Nobody did anything wrong, exactly. The deadline didn’t move. It just showed up.
Before I bought System Six, I spent years in private equity, where you looked at a quarter’s numbers before it ended, not after. That habit is the whole point of this post. Three federal tax dates land on most service businesses between now and January. Each has something you can do this week to make it boring. Boring is the goal.
Oct 15 — extended 1040 and calendar-year 1120 returns
If you filed an extension in April, here’s the part people forget: this is it. There is no further extension. October 15 is the last day to file your extended personal return, or your C corporation’s, before failure-to-file penalties stack on top of what you owe. (The extension gave you time to file, not time to pay. Interest has been running since April.)
So ask your preparer one question this week: “Is anything outstanding on my file?”
Not “How’s it going?” That question gets you “Fine.” The specific one gets you a list.
What’s usually on that list? October surprises tend to come from three places. The first is a missing K-1. If you own a piece of a partnership or S corporation — a real estate deal, a friend’s firm, a fund — you can’t finish your 1040 until it sends your share of its income. Their extended deadline was September 15, but K-1s still straggle in. The second is unreconciled books. Your preparer can’t sign a return built on a P&L whose bank balance doesn’t match the bank.
The third is the quietest: a document each side assumed the other had. Picture Leah, who runs a twelve-person consulting firm outside Seattle. Her CPA assumed the bookkeeper had sent the fixed asset schedule. The bookkeeper assumed Leah had. Leah assumed it was handled because everyone seemed so relaxed. It surfaced on October 9th. It got done — at the cost of a weekend nobody wanted to give up.
The fix is one email, everyone copied, sent today. One of our clients, Paul, valued more than clean books (his auditors found zero errors). He valued that our team kept “seeing challenges coming down the pike.” That’s all the outstanding-items question is. Looking down the pike while there’s still road left.
Nov 2 — Q3 Form 941
This one slips past owners because it feels automatic. Form 941 is your quarterly payroll tax return: the federal income tax you withheld from employees, plus both halves of Social Security and Medicare. The Q3 return covers July through September. It’s normally due October 31, but that’s a Saturday in 2026, so the deadline moves to Monday, November 2. Employers who made timely deposits in full payment of the quarter’s taxes get until November 10.
Most owners hear “941” and relax, because the payroll provider handles it. Maybe. This distinction is worth five minutes of your time.
Some providers file the 941. When you signed up, you authorized them as your reporting agent (IRS Form 8655), and they make the deposits, sign the return and submit it. Others only prepare it. They calculate the numbers and generate a clean PDF, which then sits in a dashboard waiting for someone at your company to sign, file and sometimes pay. Both kinds will show you a Form 941. Only one of them sent it.
Which kind do you have? Log in and look for a filed status or an IRS acknowledgment, not just a document. If you can’t tell, email them: “Did you file our Q3 941, or did you prepare it for us to file?”
Why does it matter so much? Because the penalty falls on the business either way. The IRS doesn’t mail the notice to your payroll company. It comes to you, with your EIN at the top.
Jan 15 — Q4 estimated payment
This one surprises people: your January payment is mostly decided by December 31. The check goes out in January, but the number gets set in the next 90 days, by decisions you’re about to make anyway.
Do you run the bonuses in December or January? Buy the new laptops and the conference-room build-out before year-end, or after? Push hard to collect December receivables, or let a few invoices go out on January 2? If you keep your books on a cash basis, each of those calls moves taxable income from one year into the other. Each one moves cash, too.
A lesser-known wrinkle for S corporation owners: tax withheld from your own W-2 wages generally counts as paid evenly across the year, even if it all comes out of one December paycheck. Estimated payments count on the day you make them. So an owner who’s behind can sometimes catch up with a year-end bonus and extra withholding. Talk to your preparer first. And if your business is a C corporation, its own fourth-quarter estimate is due December 15.
Make these calls against a one-page Q4 projection. Not a forty-tab model. One page.
What goes on it? Start with actual results through September, from reconciled books. Add your best estimate of October through December revenue, client by client if you can — service businesses usually know who’s billing what. Then expected expenses, including payroll, any bonus you’re weighing and the purchases on your list. That gives you projected taxable income. Under it, write what you’ve already paid: three estimates plus withholding. Next, your safe-harbor target, generally 100% of last year’s tax, or 110% if your adjusted gross income topped $150,000. Hit that and you avoid underpayment penalties however the year shakes out. The gap between paid and needed is your January 15 number.
Last line: cash on hand. Because the right answer on paper isn’t the right answer if the account can’t cover it.
Another client, Marcus, says he appreciates that our team will “look around corners.” A one-page projection does exactly that, while you can still change what’s there.
State and local dates are yours to check
Everything above is federal. State and local deadlines vary. Washington has no personal income tax, but B&O excise returns follow their own schedule. California runs its own estimated payment calendar through the Franchise Tax Board. Cities often add more. Check your own state and city calendars this week, and write those dates next to these three.
Three dates, three small moves
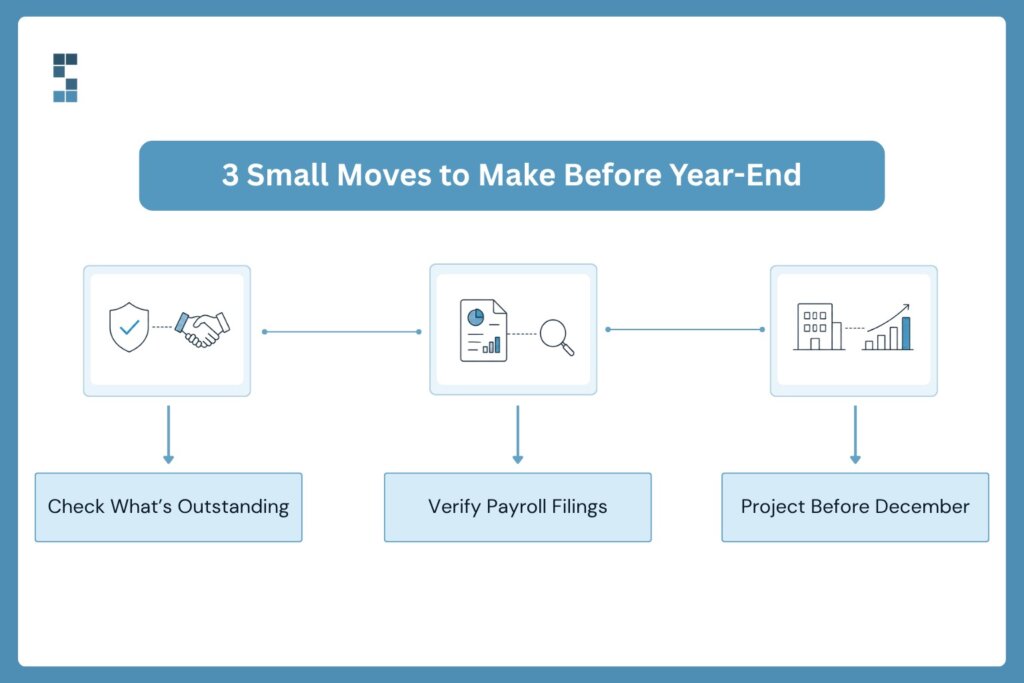
Ask your preparer what’s outstanding. Confirm your payroll provider filed your 941, not just prepared it. Build the one-page projection before December makes your decisions for you.
None of it takes long. All of it is easier in October than in January.
If you’d like a second set of eyes, we’ll review your file with you: what’s open, what’s coming due, and what the next 90 days could change. You can start here: systemsix.com/get-started.
Frequently asked questions
What happens if I miss the October 15 extended deadline?
File as soon as you can. The failure-to-file penalty is generally a percentage of the unpaid tax for each month the return is late, and interest keeps accruing on any balance. If you’re owed a refund, there’s usually no penalty, but there’s no upside to waiting either.
Do I really get until November 10 to file my Q3 Form 941?
Only if you deposited all of the quarter’s taxes on time and in full. If any deposit was late or short, the deadline is November 2.
Can I skip the January 15 estimated payment?
Individuals who file their full 2026 return and pay the entire balance by February 1, 2027 (January 31 falls on a Sunday) generally don’t need to make the fourth-quarter payment. With K-1s and year-end books still in motion, few business owners are ready that early, so plan to pay on January 15.
This post offers general information for US businesses and owners filing on a calendar year. It isn’t tax advice, and your situation may differ. Check all dates against current IRS guidance, including any disaster-relief postponements that apply to your area, and confirm state and local deadlines with the relevant agencies.
Page 2 of 17«12345...10...»Last »