by Chris Williams | Oct 6, 2026 | Blog
The short answer
Only if you were going to buy it anyway. A deduction returns your marginal tax rate, not the full purchase price, so spending money you didn’t need to spend still leaves you poorer. Where year-end spending does pay off is timing: pulling a purchase you’d make in the new year into December. And some of the best year-end moves don’t involve buying anything at all.
Picture Joel on December 28th. He runs a small marketing agency, and he’s standing in a computer store with a cart full of gear: two new monitors, a laptop he’ll probably give to an intern, a standing desk still in the box. Somebody told him he should “spend some money for taxes.” So here he is.
I get it. Nobody likes writing a check to the IRS, and buying something feels better than paying a bill. But before you load up the cart, let’s do the math most people skip.
What’s the math people skip?
A deduction doesn’t give you back what you spent. It gives you back your marginal tax rate on what you spent. That’s it.
Say your combined federal and state rate is roughly 30%. You spend $10,000 on things you didn’t need. The deduction saves you about $3,000 in tax. So you’re about $7,000 worse off than if you’d done nothing. Plus you own a standing desk you didn’t want.
Put another way: you just spent a dollar to save thirty cents. Would you do that anywhere else in your business?
That’s why the honest answer to “Should I spend money to save taxes?” is almost always no. Spending to save taxes is like paying for a meal you’re not hungry for because the restaurant offered a discount. The discount is real. The meal still costs you.
Where does year-end spending actually work?
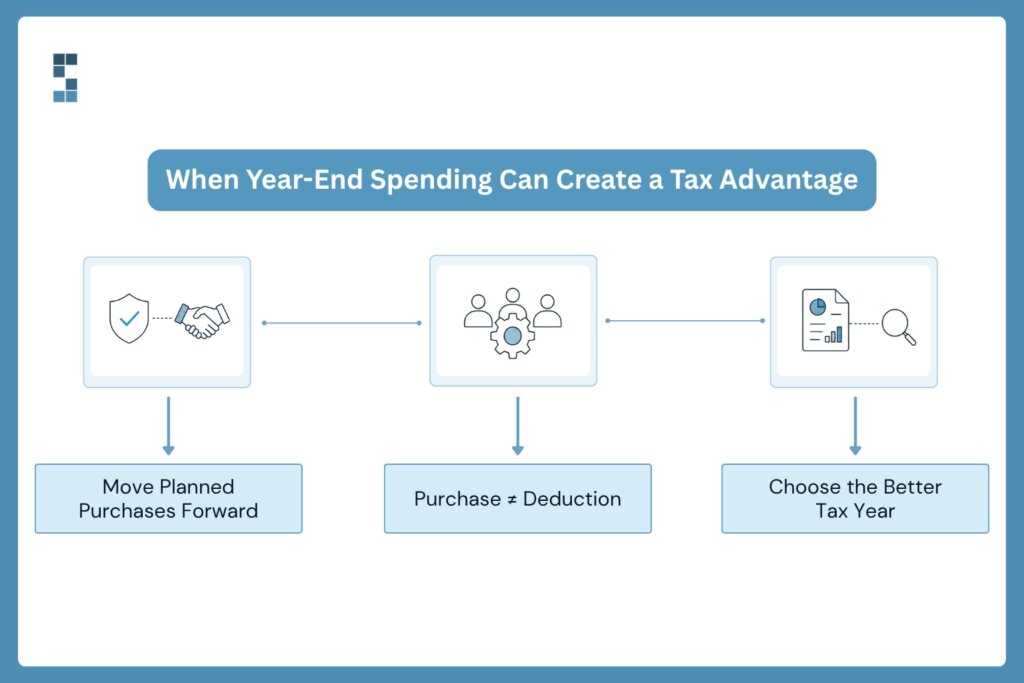
Timing. That’s where the real money is.
If a purchase is already on next year’s list, and you’d buy it in February no matter what, pulling it into December can move the deduction a full year earlier. You were spending the money either way. Now you get the tax benefit twelve months sooner, which means more cash in your pocket while you need it.
What kinds of purchases? Equipment you’ve already planned to replace: the aging laptops, the server, the furniture for the new hire starting in January. Software or subscriptions you’d renew anyway, prepaid within the allowed window. For a cash-basis business, that generally means the benefit doesn’t run past twelve months or the end of next year, whichever comes first. And everyday supplies you burn through on a predictable schedule.
There are a few catches. Equipment usually has to be placed in service by December 31, not just ordered or paid for. A laptop sitting in a warehouse doesn’t count. Whether you can deduct the full cost this year depends on the rules for immediate expensing, called Section 179 and bonus depreciation, and those limits have changed more than once lately. Your accounting method matters, too. If you’re on the accrual basis, paying in December doesn’t automatically pull the deduction forward the way it does on a cash basis. So confirm the current limits and how they apply to you with a tax professional before you buy.
One more wrinkle worth knowing. If you expect next year to be a much bigger year, a deduction might be worth more next year than this one. Pulling it forward isn’t automatically a win. It’s a judgment call, and it’s worth making on purpose.
What else can you do that doesn’t involve buying things?
Quite a lot, actually. These are often the better moves.
The first is timing invoices and collections. If you file on a cash basis, income counts when you receive it. Sending a few invoices on January 2nd instead of December 20th can shift that income into next year. There’s a limit, though. If a client hands you a check in December, you can’t just leave it in a drawer and call it January income. The IRS treats money you could have collected as received.
The second is retirement contributions. A contribution to a retirement plan can lower your taxable income without buying anything you don’t need, and the money stays yours. Deadlines differ by plan type. Some plans need to be in place before year-end for certain contributions, while others can be set up and funded later. That’s exactly why you want to ask early.
The third is paying bonuses on time. A cash-basis business deducts bonuses in the year it pays them, so a bonus run in December lands this year and one in January lands next year. Accrual-basis businesses can sometimes deduct bonuses earned this year if they pay them within two and a half months after year-end, though the rules differ for owners and their families. Either way, payroll has to actually run, and that takes planning.
Why does this conversation belong in early November?
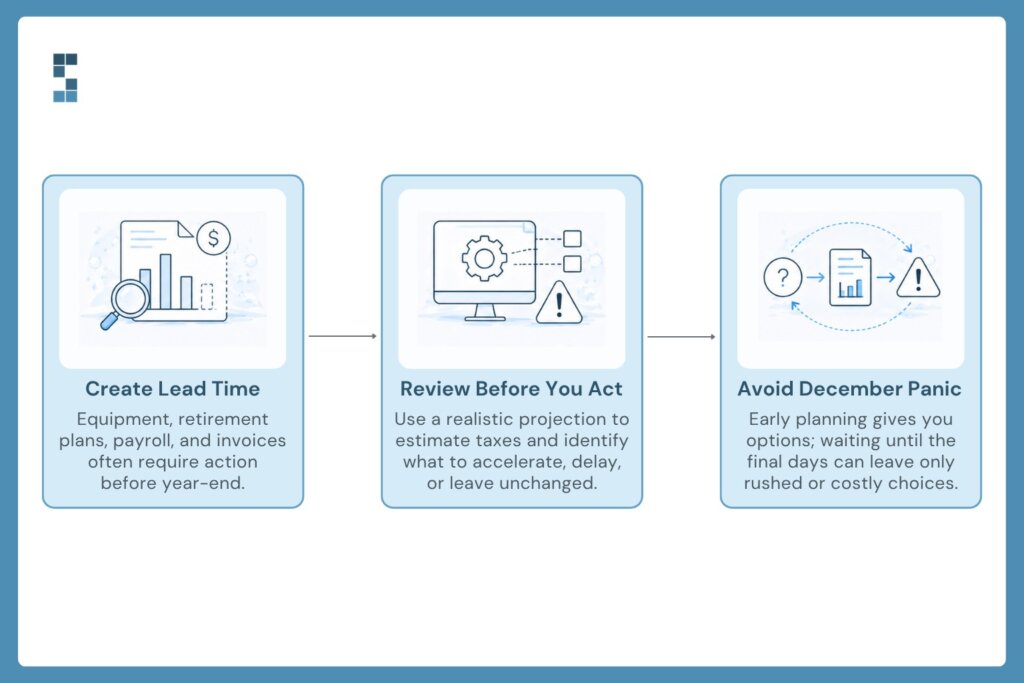
Because by December 30th, the only options left are the bad ones.
Think about everything above. Equipment has to be ordered, delivered and set up. Retirement plans may need paperwork. Bonuses need a payroll run. Invoices need a decision before they go out. Every good move takes a little lead time. The one move that doesn’t is the cart full of things you didn’t need.
Early November gives you room. You can look at a realistic projection of the year, see roughly what you’ll owe, and decide what’s worth pulling forward, pushing back or leaving alone. That’s a calm conversation. The December 28th version is a panicked one.
This is where a good partner earns their keep. One of our clients, Aiko, described it as having a team that’s “open to questions and equipped with a lot of recommendations.” That’s what year-end planning should feel like. Not a scramble. A short list of good choices, made on purpose.
Spend on purpose, not for a deduction
Here’s the rule I’d tape to the wall: if you’d buy it anyway, consider buying it sooner. If you wouldn’t, keep your money. A tax deduction is a discount, not a reason to shop.
If you’d like to walk through your own year before the options narrow, we’ll set up a year-end planning call. You can start here: systemsix.com/get-started.
Frequently asked questions
Does a $10,000 business purchase reduce my taxes by $10,000?
No. It reduces your taxable income by up to $10,000, which cuts your tax by roughly your marginal rate. At a combined 30%, that’s about $3,000.
Can I deduct equipment I order in December but receive in January?
Generally not for this year. Equipment usually has to be placed in service, meaning ready and available for use, by December 31. Confirm the details with your tax professional.
Does prepaying next year’s expenses help on an accrual basis?
Usually much less than on a cash basis, because accrual-basis businesses deduct expenses when they’re incurred, not simply when they’re paid. Your preparer can tell you which method you use and what applies.
This post offers general information for US businesses filing on a calendar year. It isn’t tax advice, and your situation may differ. Verify all limits and rules, including Section 179, bonus depreciation, prepaid expense and retirement plan deadlines, against current IRS guidance before acting.
by Chris Williams | Oct 2, 2026 | Blog
The short answer
When money you take out of the business as an owner gets recorded as an expense, your profit and loss statement shows the business earning less than it really does. Day to day, nobody notices. But the moment a lender, a buyer or an investor relies on those numbers, the understatement shrinks your loan, your valuation and your credibility. Finding it takes about five minutes. Fixing it now is far easier than fixing it in the middle of a deal.
I spent years in private equity reading quality-of-earnings reports. Hundreds of pages, most of them dull, written by accountants whose whole job is to figure out what a business really earns. And one finding showed up so often I could almost predict it: the owner’s own money was sitting in the expense accounts.
It never looked dramatic. A line called “Consulting — G. Ruiz.” A “Misc” account with a suspiciously steady $10,000 a month. Small things. But small things in the wrong account have a way of turning up at the worst possible moment.
Let me show you why, and how to check your own books before anyone else does.
Why does this happen?
Picture the end of the month. Your bookkeeper is working through the bank feed, and there’s a $10,000 transfer to your personal checking account. Money left the business. Something has to be coded. The software wants a category, and “expense” is the easiest box to tick. It’s the path of least resistance, so it wins.
Nobody’s hiding anything. Often the bookkeeper simply wasn’t told what the transfer was, or the chart of accounts never had an owner’s equity account set up in the first place. Personal charges on the company card get the same treatment — your kid’s tuition lands in “Office expense” because there was nowhere else to put it.
And because the money really did leave, the bank balance still reconciles. The books look clean. They’re just wrong.
What does it cost you?
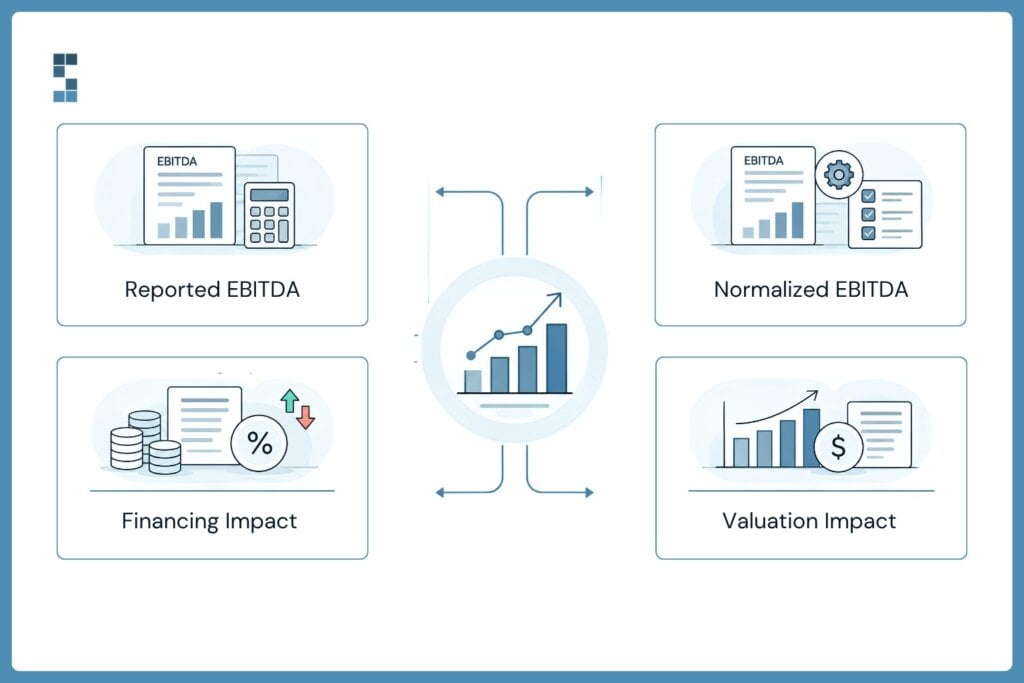
Here’s the part that surprises owners: on a normal Tuesday, it costs almost nothing. Your cash is your cash, wherever it’s coded. (It can create a tax problem, since a draw isn’t deductible, so it’s worth raising with your CPA.) The real cost arrives when someone outside the business has to trust your P&L.
Let’s use round numbers. Gabe runs a $2 million engineering consulting firm. His P&L shows $200,000 of EBITDA (earnings before interest, taxes, depreciation and amortization, a common stand-in for operating profit). Buried in his expenses is $120,000 he took home as draws over the year. His real EBITDA is $320,000.
Now watch what happens.
A lender sizing a loan at three times EBITDA offers him $600,000 instead of $960,000. A buyer paying four times earnings starts at $800,000 instead of $1.28 million — a $480,000 gap, before anyone negotiates a thing. To be fair, a buyer will also subtract what it would cost to pay someone to do Gabe’s job, so the true figure lands somewhere in between. But that conversation starts from his real numbers, not from a mistake. And a bank calculating debt-service coverage, with $160,000 of annual payments on the table, sees 1.25 times coverage on his reported numbers, right on the line many lenders draw. On his real numbers it’s 2.0 times, a comfortable yes.
Same business. Same clients. Same people. A very different answer.
How do you check your books in five minutes?
Open your trailing-12-month P&L. Scan the expense accounts and look for anything that reads like a person rather than a vendor. A name. An account called “Misc” or “Reimbursement.” One large, round number that shows up every single month, like clockwork. Vendors send invoices with odd amounts. Owners transfer round ones.
Then flip to the balance sheet. Look in the equity section for an owner’s draw or distribution account. Does it have real activity — a balance that grows across the year? If there’s nothing there, but you know money has clearly been leaving the business for your benefit, the draws are in the wrong place. That’s the tell.
That’s it. Five minutes, maybe ten if you pour a coffee first.
How do you fix it?
Start by reclassifying the draws. Your bookkeeper pulls the transactions out of the expense accounts and moves them to equity, month by month, with a short note on each. Go back at least as far as the period a lender or buyer will review, usually the last two or three years.
Next, set up the right equity accounts for your entity type, because the label matters. If you’re a sole proprietor or a single-member LLC, you’ll use an owner’s draw account that rolls into owner’s equity at year-end. In a multi-member LLC taxed as a partnership, each member gets their own draw and capital account. One wrinkle: guaranteed payments to partners for their work are deductible, so not every payment to a partner is a draw. If you’re an S corporation, your pay for working in the business runs through payroll as a reasonable W-2 salary, and that is an expense. Anything you take above it is a shareholder distribution, recorded in equity.
Finally, ask your bookkeeper to keep it clean going forward. A simple rule works: every transfer to an owner gets coded to equity unless someone documents a business reason. When we clean up a client’s books, this is usually one of the first changes. One of them, Trevor, put the result simply: “We are in a much better place today than we were twelve months ago.” That’s what this fix buys you. Not drama. Just numbers you can stand behind.
Why is it harder to untangle mid-deal?
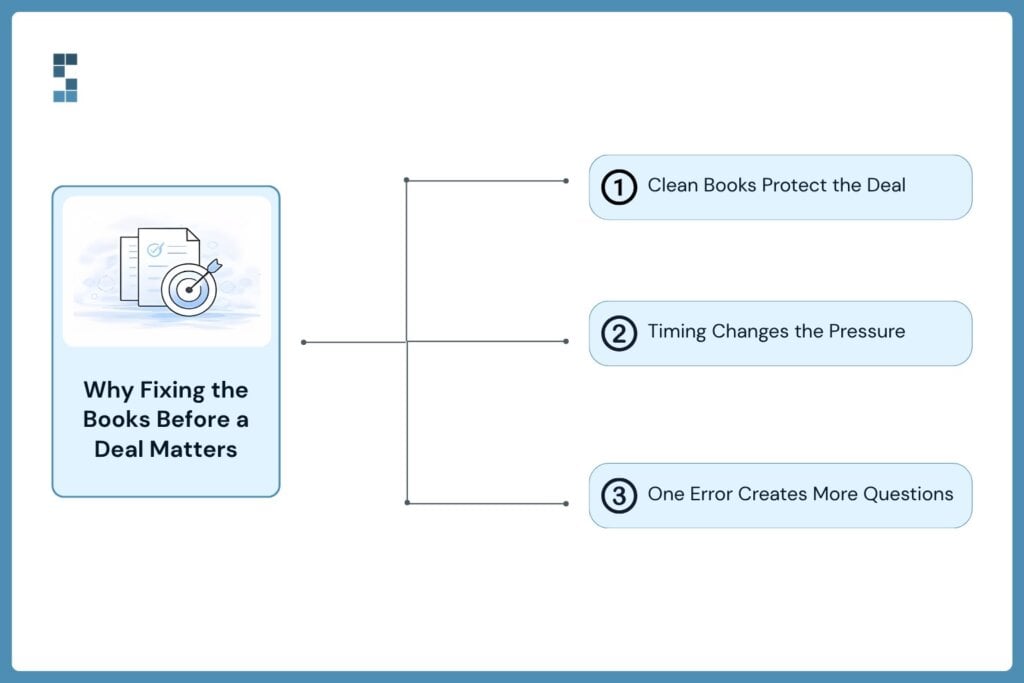
Because a deal changes who’s asking and how much time you have.
In private equity, I watched diligence teams turn over every account in the general ledger. When they found owner spending in the expense lines, they didn’t just take the seller’s word for it. Each item had to be proven with bank statements, receipts and an explanation, often for three years at once, on a deadline, while the owner was also trying to run the company. Anything they couldn’t verify, they left out. And once a buyer finds one miscoded account, they start wondering about the others. The questions multiply. The timeline stretches. Sometimes the price gets renegotiated.
I saw it from the other side, too. When I bought System Six with an SBA loan, the bank underwrote the deal from the seller’s financials, line by line. Clean books made that process faster and calmer for everyone.
Here’s the thing: the work to fix this is identical whether you do it now or during diligence. Now, you do it calmly, on your own schedule, with no one watching. During a deal, you do it under a microscope with money on the line. Which would you rather?
If you’re thinking about a sale or an investment, our guide to quality-of-earnings reports walks through what a diligence team will look for. And if you’d like us to run the five-minute check with you and tell you what we find, we’re happy to: systemsix.com/get-started.
Frequently asked questions
Are owner draws a deductible business expense?
No. A draw or distribution is the owner taking money out of the business, not a cost of running it. W-2 salary paid to an S corporation owner through payroll and guaranteed payments to partners are treated differently, so ask your CPA how your entity type applies.
Is it called a draw or a distribution?
It depends on your entity. Sole proprietors and LLC members typically take draws. S corporation shareholders take distributions. Either way, it belongs in the equity section of the balance sheet, not on the P&L.
If I reclassify past draws, do I need to amend old tax returns?
Possibly, if the change affects the taxable income on a return you’ve already filed. That’s a question for your tax preparer, and it’s another reason to catch the problem early.
This post offers general information for owners of US small businesses. It isn’t tax or legal advice, and the right treatment depends on your entity type and circumstances. Talk with your CPA or attorney before making changes to your books or filed returns.
by Chris Williams | Sep 28, 2026 | Blog
The short answer
Three federal dates matter to calendar-year service businesses this quarter. October 15 is the final deadline for extended 1040 and calendar-year 1120 returns, and there’s no second extension. November 2 is the deadline for your Q3 Form 941 (October 31 falls on a Saturday), or November 10 if you made every deposit on time and in full. January 15, 2027 is the fourth-quarter estimated tax payment, and the decisions that set its size happen between now and December 31. State and local deadlines run on their own calendars, so check yours.
Every fall I get some version of the same phone call. The owner sounds calm, but they’re talking a little too fast. Their CPA just emailed. Something’s missing. The return is due in eight days.
Nobody did anything wrong, exactly. The deadline didn’t move. It just showed up.
Before I bought System Six, I spent years in private equity, where you looked at a quarter’s numbers before it ended, not after. That habit is the whole point of this post. Three federal tax dates land on most service businesses between now and January. Each has something you can do this week to make it boring. Boring is the goal.
Oct 15 — extended 1040 and calendar-year 1120 returns
If you filed an extension in April, here’s the part people forget: this is it. There is no further extension. October 15 is the last day to file your extended personal return, or your C corporation’s, before failure-to-file penalties stack on top of what you owe. (The extension gave you time to file, not time to pay. Interest has been running since April.)
So ask your preparer one question this week: “Is anything outstanding on my file?”
Not “How’s it going?” That question gets you “Fine.” The specific one gets you a list.
What’s usually on that list? October surprises tend to come from three places. The first is a missing K-1. If you own a piece of a partnership or S corporation — a real estate deal, a friend’s firm, a fund — you can’t finish your 1040 until it sends your share of its income. Their extended deadline was September 15, but K-1s still straggle in. The second is unreconciled books. Your preparer can’t sign a return built on a P&L whose bank balance doesn’t match the bank.
The third is the quietest: a document each side assumed the other had. Picture Leah, who runs a twelve-person consulting firm outside Seattle. Her CPA assumed the bookkeeper had sent the fixed asset schedule. The bookkeeper assumed Leah had. Leah assumed it was handled because everyone seemed so relaxed. It surfaced on October 9th. It got done — at the cost of a weekend nobody wanted to give up.
The fix is one email, everyone copied, sent today. One of our clients, Paul, valued more than clean books (his auditors found zero errors). He valued that our team kept “seeing challenges coming down the pike.” That’s all the outstanding-items question is. Looking down the pike while there’s still road left.
Nov 2 — Q3 Form 941
This one slips past owners because it feels automatic. Form 941 is your quarterly payroll tax return: the federal income tax you withheld from employees, plus both halves of Social Security and Medicare. The Q3 return covers July through September. It’s normally due October 31, but that’s a Saturday in 2026, so the deadline moves to Monday, November 2. Employers who made timely deposits in full payment of the quarter’s taxes get until November 10.
Most owners hear “941” and relax, because the payroll provider handles it. Maybe. This distinction is worth five minutes of your time.
Some providers file the 941. When you signed up, you authorized them as your reporting agent (IRS Form 8655), and they make the deposits, sign the return and submit it. Others only prepare it. They calculate the numbers and generate a clean PDF, which then sits in a dashboard waiting for someone at your company to sign, file and sometimes pay. Both kinds will show you a Form 941. Only one of them sent it.
Which kind do you have? Log in and look for a filed status or an IRS acknowledgment, not just a document. If you can’t tell, email them: “Did you file our Q3 941, or did you prepare it for us to file?”
Why does it matter so much? Because the penalty falls on the business either way. The IRS doesn’t mail the notice to your payroll company. It comes to you, with your EIN at the top.
Jan 15 — Q4 estimated payment
This one surprises people: your January payment is mostly decided by December 31. The check goes out in January, but the number gets set in the next 90 days, by decisions you’re about to make anyway.
Do you run the bonuses in December or January? Buy the new laptops and the conference-room build-out before year-end, or after? Push hard to collect December receivables, or let a few invoices go out on January 2? If you keep your books on a cash basis, each of those calls moves taxable income from one year into the other. Each one moves cash, too.
A lesser-known wrinkle for S corporation owners: tax withheld from your own W-2 wages generally counts as paid evenly across the year, even if it all comes out of one December paycheck. Estimated payments count on the day you make them. So an owner who’s behind can sometimes catch up with a year-end bonus and extra withholding. Talk to your preparer first. And if your business is a C corporation, its own fourth-quarter estimate is due December 15.
Make these calls against a one-page Q4 projection. Not a forty-tab model. One page.
What goes on it? Start with actual results through September, from reconciled books. Add your best estimate of October through December revenue, client by client if you can — service businesses usually know who’s billing what. Then expected expenses, including payroll, any bonus you’re weighing and the purchases on your list. That gives you projected taxable income. Under it, write what you’ve already paid: three estimates plus withholding. Next, your safe-harbor target, generally 100% of last year’s tax, or 110% if your adjusted gross income topped $150,000. Hit that and you avoid underpayment penalties however the year shakes out. The gap between paid and needed is your January 15 number.
Last line: cash on hand. Because the right answer on paper isn’t the right answer if the account can’t cover it.
Another client, Marcus, says he appreciates that our team will “look around corners.” A one-page projection does exactly that, while you can still change what’s there.
State and local dates are yours to check
Everything above is federal. State and local deadlines vary. Washington has no personal income tax, but B&O excise returns follow their own schedule. California runs its own estimated payment calendar through the Franchise Tax Board. Cities often add more. Check your own state and city calendars this week, and write those dates next to these three.
Three dates, three small moves
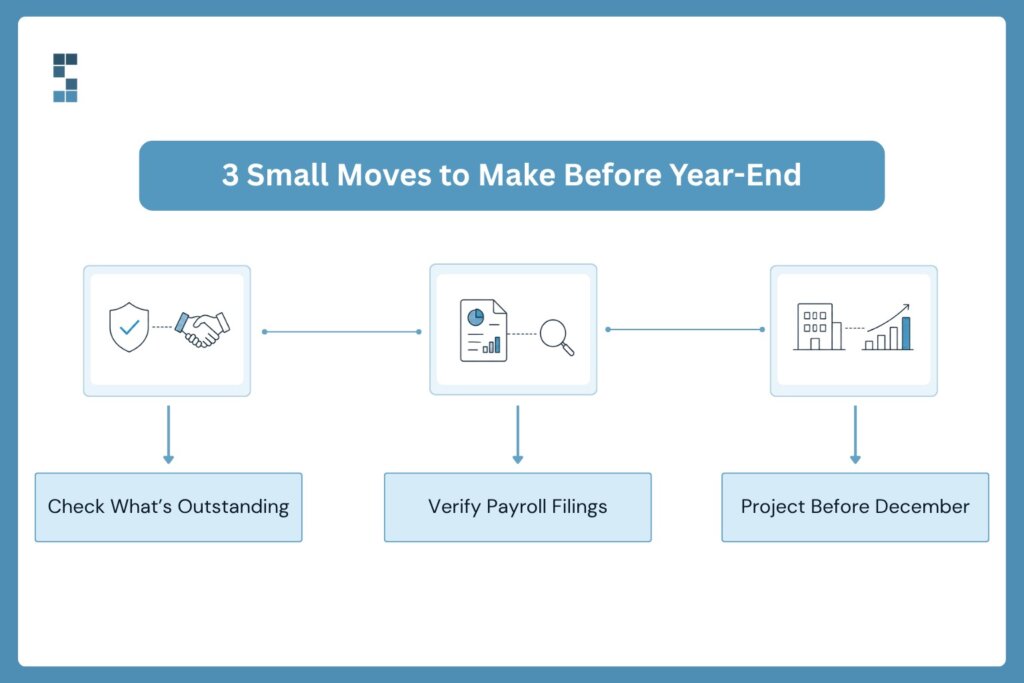
Ask your preparer what’s outstanding. Confirm your payroll provider filed your 941, not just prepared it. Build the one-page projection before December makes your decisions for you.
None of it takes long. All of it is easier in October than in January.
If you’d like a second set of eyes, we’ll review your file with you: what’s open, what’s coming due, and what the next 90 days could change. You can start here: systemsix.com/get-started.
Frequently asked questions
What happens if I miss the October 15 extended deadline?
File as soon as you can. The failure-to-file penalty is generally a percentage of the unpaid tax for each month the return is late, and interest keeps accruing on any balance. If you’re owed a refund, there’s usually no penalty, but there’s no upside to waiting either.
Do I really get until November 10 to file my Q3 Form 941?
Only if you deposited all of the quarter’s taxes on time and in full. If any deposit was late or short, the deadline is November 2.
Can I skip the January 15 estimated payment?
Individuals who file their full 2026 return and pay the entire balance by February 1, 2027 (January 31 falls on a Sunday) generally don’t need to make the fourth-quarter payment. With K-1s and year-end books still in motion, few business owners are ready that early, so plan to pay on January 15.
This post offers general information for US businesses and owners filing on a calendar year. It isn’t tax advice, and your situation may differ. Check all dates against current IRS guidance, including any disaster-relief postponements that apply to your area, and confirm state and local deadlines with the relevant agencies.
by Chris Williams | Sep 24, 2026 | Blog
The short answer: Getting the most from your bookkeeper comes down to four habits on your side of the relationship. Feed them clean, timely inputs so they’re not chasing you for receipts and answers. Set a communication rhythm, a quick weekly touchpoint, a monthly review, a quarterly look ahead, so questions don’t pile up. Treat them as your finance team rather than a vendor, and ask them real questions. And share context early, before a hire, a new entity, or a big contract, so they can plan ahead instead of cleaning up after. Do those four things and the same bookkeeper delivers several times the value.
Nadia had a good bookkeeper and got almost nothing out of her. Not because the bookkeeper was bad. Because Nadia treated the relationship like a utility bill: pay it monthly, expect it to work, never think about it otherwise. Receipts went in when Nadia remembered. Questions from the bookkeeper sat in her inbox for a week. Reports arrived and got filed unread. Then one afternoon Nadia mentioned, in passing, that she’d hired two contractors in a new state three months earlier. The bookkeeper went quiet, then asked why she was hearing about it now. There were filings due. There’d been filings due for a while.
Here’s what almost nobody tells you when you hire financial help: the quality of what you get back depends heavily on what you put in. A bookkeeper working with stale inputs, unanswered questions, and no context can only ever record your past. A bookkeeper you actually work with can help you shape what’s coming. Same person, same fee, wildly different result. So let’s talk about your half of the deal, the four habits that turn a bookkeeper you pay into a finance team you use.
What should you be sending your bookkeeper, and when?
Start with inputs, because everything downstream depends on them. Your bookkeeper builds your books out of what you hand over, and the two things that quietly wreck the output are late data and unanswered questions.
Late data first. Receipts that arrive in a shoebox at quarter-end, expense reports submitted whenever someone gets around to it, time entries logged from memory a week later: each one forces your bookkeeper to reconstruct rather than record, and reconstruction is where errors creep in. The fix isn’t heroic. It’s a rhythm. Snap the receipt when you get it, submit expenses weekly, log time daily. Most of this can be pushed to an app on your phone so the friction drops to almost nothing. Clean inputs on a schedule are the single biggest lever you control.
Then the questions. When your bookkeeper asks what a $1,200 charge was for, or which project a contractor invoice belongs to, that question is a transaction sitting in limbo. Every day it waits, your books are a little less current and your close slips a little further. Make a habit of clearing those same-day, even if the answer is two words. One System Six client, Warn, put it simply: the team keeps the books completely up to date, and issues get addressed immediately. That speed runs both directions. Your fast answers are what let your bookkeeper be fast.
How often should you talk to your bookkeeper?
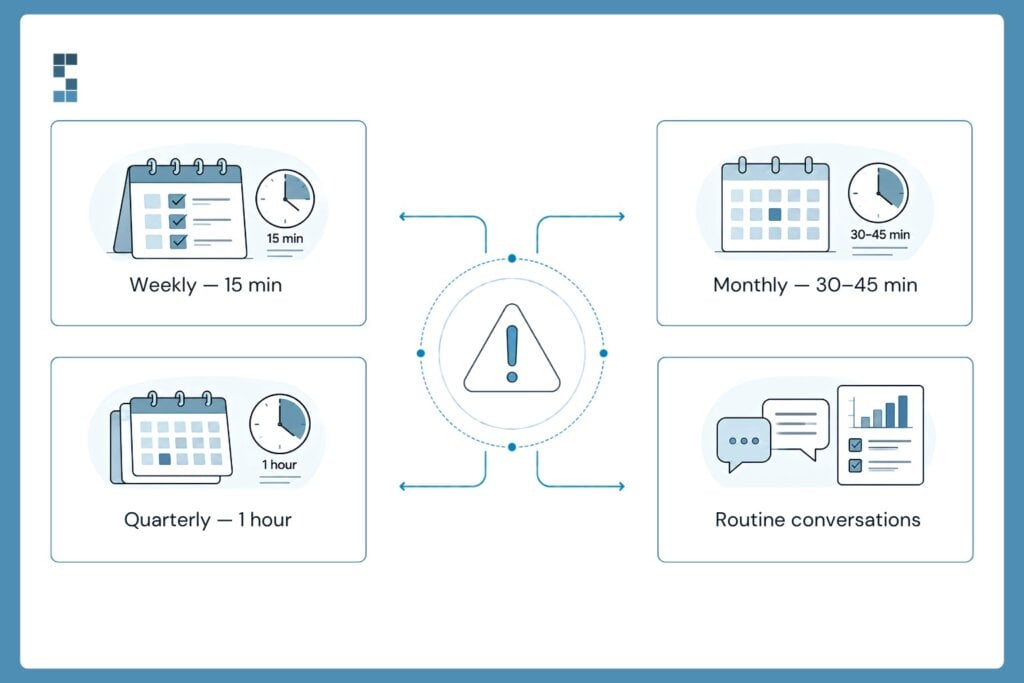
More than most owners do, and on a schedule, so it stops depending on someone remembering. A good cadence has three layers, and none of them take much time.
A short weekly touchpoint, fifteen minutes or a quick message thread, to clear open questions, flag anything unusual coming up, and check that nothing’s stuck. This is the layer that stops small things from becoming big things. A monthly review, thirty to forty-five minutes with the financials in front of you both, to walk through what happened, what surprised anyone, and what the numbers suggest for next month. Not a report handoff; a conversation about it. And a quarterly look ahead, an hour to step back from the month-to-month and talk about the next ninety days: hiring plans, cash needs, big contracts, tax positioning.
Why does the structure matter so much? Because without it, communication defaults to crisis. You talk to your bookkeeper when something’s wrong, which means every conversation is stressful and reactive. With a rhythm in place, most conversations are routine and forward-looking, and the crises mostly stop happening, because you caught them at the weekly touchpoint three weeks earlier. Aiko, a small business owner working with System Six, described the team as always open to questions and full of recommendations. That’s what a real cadence produces: a standing channel where questions and recommendations flow both ways, instead of a phone that only rings when something’s broken.
How do you get strategic value, not just clean books?
This is the habit that separates owners who get bookkeeping from owners who get a finance team, and it’s mostly a shift in how you think about the person on the other end.
A vendor executes tasks. A team member thinks about your business. If you only ever send transactions and receive reports, you’ve hired a vendor, no matter how capable they are. The upgrade is asking real questions. Not “is the close done?” but “which of my service lines is actually most profitable?” Not “did that invoice get paid?” but “are my collections getting slower, and what should I do about it?” Good bookkeepers are sitting on exactly the data that answers those questions, and most of them are quietly hoping you’ll ask, because it’s far more interesting work than categorizing expenses. Rebecca, a System Six client, said the team isn’t just a vendor but friends who feel like part of her team. That doesn’t happen by accident. It happens when you treat them that way first, by bringing them the questions a team member would get.
The payoff is the difference between reports that describe your past and insight that shapes your decisions. When a client of System Six described the team as inquisitive, asking follow-on questions and looking around corners, that’s the version of the relationship where your bookkeeper has been invited far enough into the business to see what’s coming. You can’t look around corners for someone who only shows you the hallway.
Why should you tell your bookkeeper before you make a move?
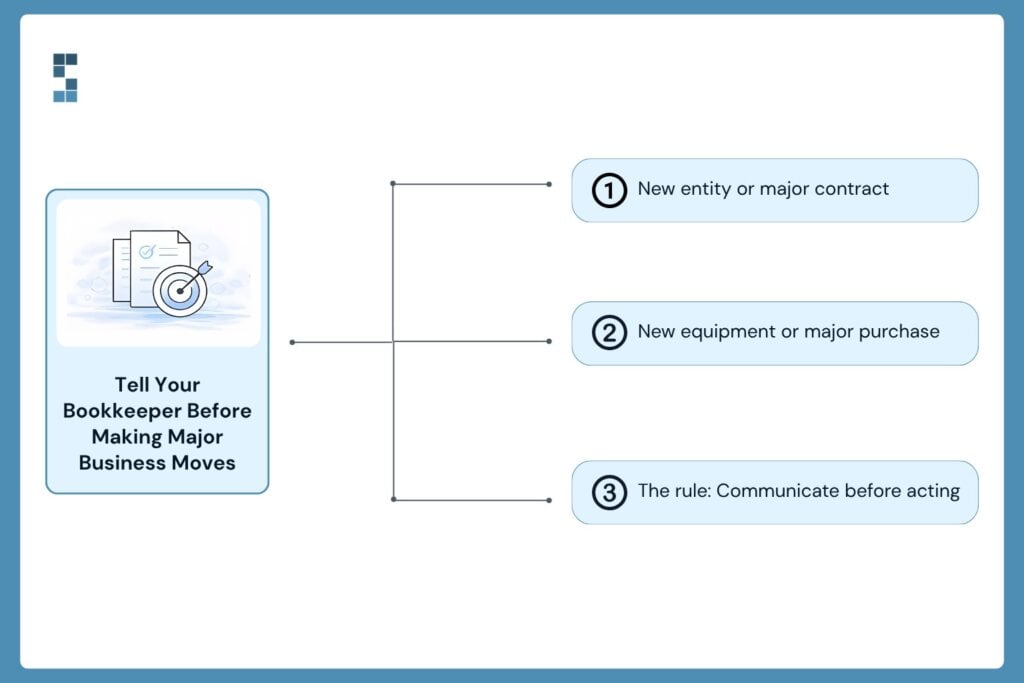
Back to Nadia’s two contractors in a new state. The mistake wasn’t hiring them. The mistake was that her bookkeeper found out three months later, when the only thing left to do was clean up.
Nearly every consequential business decision has a financial and compliance tail: a hire in a new state triggers payroll registration and tax filings; a new entity needs its own books and a plan for inter-company transactions; a big contract might need milestone billing, a different cash plan, or a fresh look at project margin; a new piece of equipment has a depreciation question attached. Told in advance, your bookkeeper sets all of that up before it’s a problem. Told afterward, they’re doing forensic work on a mess that didn’t need to exist. The rule is simple: if it changes how money moves in or out, your bookkeeper hears about it before it happens, not after. One quick heads-up costs you a sentence. The alternative costs you penalties, rework, and the exact stress you hired them to remove.
Your half of the deal
Notice what all four habits have in common. None of them require financial expertise. They require rhythm, responsiveness, and the willingness to treat your bookkeeper as someone who’s on your side of the table. Clean inputs on a schedule. A standing cadence instead of crisis calls. Real questions instead of status checks. A heads-up before the move instead of a confession after it.
Nadia changed all four, and the bookkeeper didn’t change at all. She just finally got to do the job she was capable of. That’s the thing worth sitting with: the ceiling on what your bookkeeper can deliver is usually set by you, not by them. This is the relationship System Six builds with the firms it serves, a front-line finance team rather than a back-office vendor, and it’s part of why over half of new clients arrive by referral and existing ones rate the firm an average 9.5 out of 10. People don’t refer a bookkeeper. They refer the feeling of having someone in their corner who already knows what’s coming.
So here’s the honest question. Are you getting bookkeeping, or are you getting a finance team? If the answer is the first one, the fastest fix might not be a new provider at all. It might be a better way of working with the one you already have. Send the receipt today. Answer the question today. Put the monthly review on the calendar. Then see how much more comes back.
Frequently asked questions
How often should I meet with my bookkeeper?
A three-layer cadence works well for most small firms: a short weekly touchpoint of about fifteen minutes to clear open questions and flag anything unusual, a monthly review of thirty to forty-five minutes to walk through the financials together, and a quarterly session of about an hour to plan the next ninety days. A standing rhythm keeps communication routine and forward-looking instead of reactive.
What information does my bookkeeper need from me?
Timely, clean inputs: receipts captured when you receive them, expenses submitted weekly, time logged daily, and fast answers to categorization questions, ideally same-day. Just as important is advance notice of any decision that changes how money moves, such as a new hire, a new state, a new entity, a large contract, or a major purchase, so your bookkeeper can set things up correctly before they become a problem.
How do I get more strategic value from my bookkeeper?
Ask real questions instead of status checks. Rather than asking whether the close is done, ask which service lines are most profitable, whether collections are slowing, or whether you can afford the next hire. Bookkeepers sit on the data that answers these questions and can provide far more insight when invited to, which turns a task-executing vendor into a finance team that helps shape your decisions.
What’s the difference between a bookkeeper and a finance team?
A bookkeeper records what happened; a finance team helps you decide what happens next. The difference is often less about the provider’s capability than about how you work with them. Providers given clean inputs, a regular cadence, real questions, and early context about upcoming decisions can look ahead and advise, while those given stale data and crisis-only contact can only ever report on the past.
About System Six
System Six is a Seattle-based bookkeeping and financial services firm that helps small and mid-sized businesses streamline their financial operations. We specialize in providing technology-driven financial management solutions for consulting firms, enabling owners to focus on growing their businesses without worrying about cash flow, payroll, or compliance. Our team of over 40 professionals brings an average of 10+ years of accounting experience to every client relationship, serving more than 175 businesses across the U.S. With a 9.5/10 NPS score, we deliver the financial clarity and peace of mind that consulting firm owners need to thrive. Learn more at www.systemsix.com.
by Chris Williams | Sep 17, 2026 | Blog
Every lower-middle-market deal I have ever seen prices off the same three letters. The seller says the business does two million of EBITDA, the multiple gets applied, and suddenly a number with an enormous amount of judgment baked into it is treated like a fact. Buy-side quality of earnings work exists to interrogate that number before you wire money based on it.
I have been on both sides of this. In private equity, the QoE was routine, something the deal team ordered the way you order title insurance. Then I became a searcher buying a company with my own savings and an SBA loan, and the same report stopped being routine and became the thing standing between me and a very expensive mistake. Three deals later, two of them add-ons, here is how I think about validating EBITDA as a buyer, and what a buy-side QoE should actually do for you.
What buy-side QoE actually is (and is not)
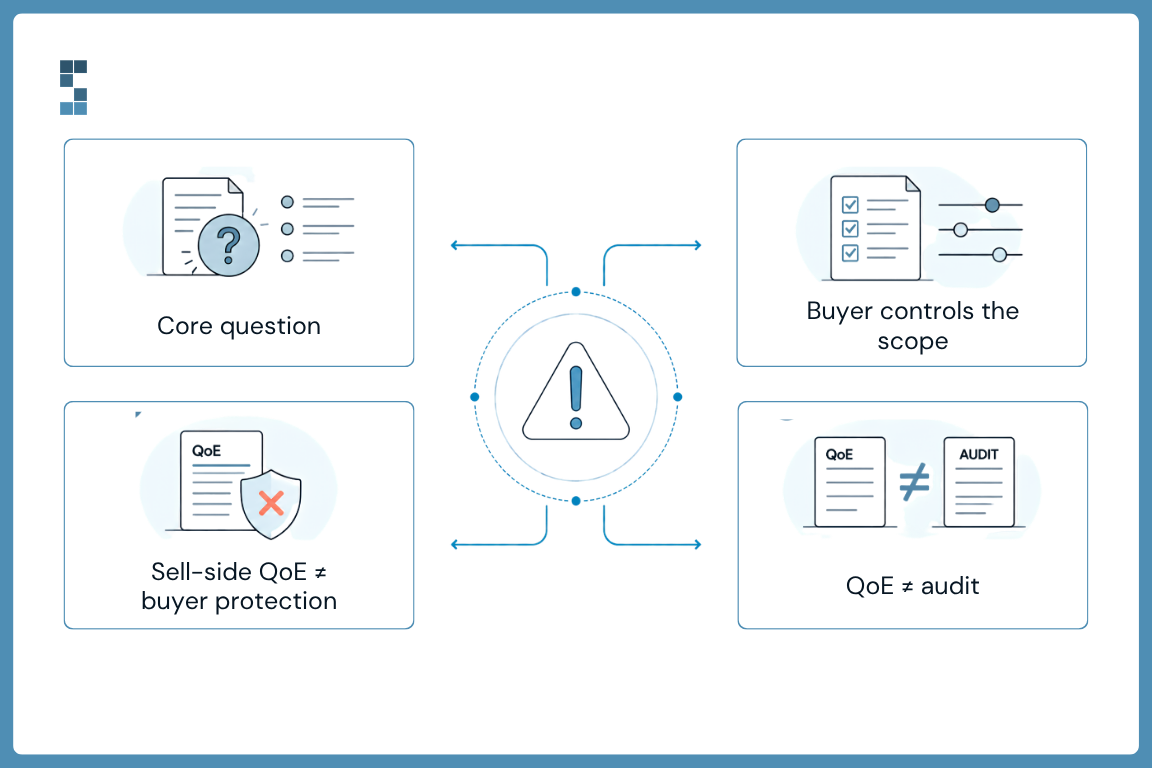
A buy-side quality of earnings engagement is diligence you commission, on the target’s numbers, answering your question: are these earnings real, recurring, and transferable to me? The report is your work product. Your team picks the scope, your team hears the findings as they surface, and the schedules are built to serve your negotiation and your financing.
That last part is what separates it from a sell-side QoE. A sell-side report is commissioned by the owner before going to market. It is genuinely useful, and a seller who has one is usually a more prepared counterpart. But it was scoped to present the business well and defend the add-backs, not to hunt for the problems that only matter to a buyer. Read it, use it, and do not rely on it. The analyses were framed by someone whose incentives point the other way.
Buy-side QoE is also not an audit. No opinion is issued and GAAP compliance is not certified, though a good team will chase every inconsistency it finds. Just know it can’t catch everything; if you don’t trust your seller, no report will 100% protect you. For a fuller treatment of that distinction, see our guide on quality of earnings vs. audits. The short version: most LMM targets have never been audited anyway, which means your diligence is the first rigorous test the numbers have ever faced.
The three EBITDAs: reported, adjusted, and run-rate
Every deal conversation is secretly about three different numbers wearing the same name.
| Reported EBITDA |
Adjusted EBITDA |
Run-rate / pro forma EBITDA |
What is it?
What the books say today, as kept by the seller |
Reported, corrected for add-backs that survive scrutiny: owner comp to market, personal expenses out, true one-time items removed, related-party amounts marked to market |
Adjusted, then projected forward for known changes: a signed price increase, a lost customer, a new lease at market rent |
Where it sits in the negotiation
Where negotiations start |
Where deals should price |
Where sellers want to price, and where buyers should be most skeptical |
The QoE’s core deliverable is the bridge between the first two: a line-by-line walk from reported to adjusted EBITDA where every adjustment is evidenced and defensible. Run-rate adjustments deserve extra suspicion as a class. Some are legitimate, like a signed lease change. Many are hope dressed as arithmetic: annualized best quarters, unsigned price increases, cost savings you will supposedly capture. My rule as a buyer: pro forma adjustments must be contractual, not aspirational, before they earn a place in the number you pay on.
Add-backs: where LMM deals are won and lost
In the lower middle market, the gap between reported and adjusted EBITDA is usually dominated by add-backs, and this is where owner-operated businesses get interesting. The owner has been running the company partly as a business and partly as a lifestyle, and untangling the two is the work.
The add-backs that generally survive scrutiny: owner compensation normalized to the market cost of the person you will actually hire to replace them, genuinely personal expenses (the vehicle, the family cell phones, the country club), true one-time items like a lawsuit settlement or a flood repair, and related-party amounts restated to market, rent above all.
The ones that fail: recurring items dressed as one-time (the fourth consecutive year of one-time legal fees), below-market wages for family members who do real work and will need real replacements, the marketing spend the seller cut to dress up the trailing twelve months, and bonuses reclassified as discretionary when the team has received them every year for a decade and expects them in month one of your ownership.
Two tests cut through most arguments. First, the replacement test: will this cost genuinely not exist under my ownership, at market rates, with the team I need to retain? Second, the lender test: will a credit committee accept this adjustment when my financing depends on it? An add-back that fails either test is not an adjustment; it is a negotiating position. Our add-backs deep dive covers the full taxonomy.
Revenue quality: EBITDA is only as good as the revenue under it
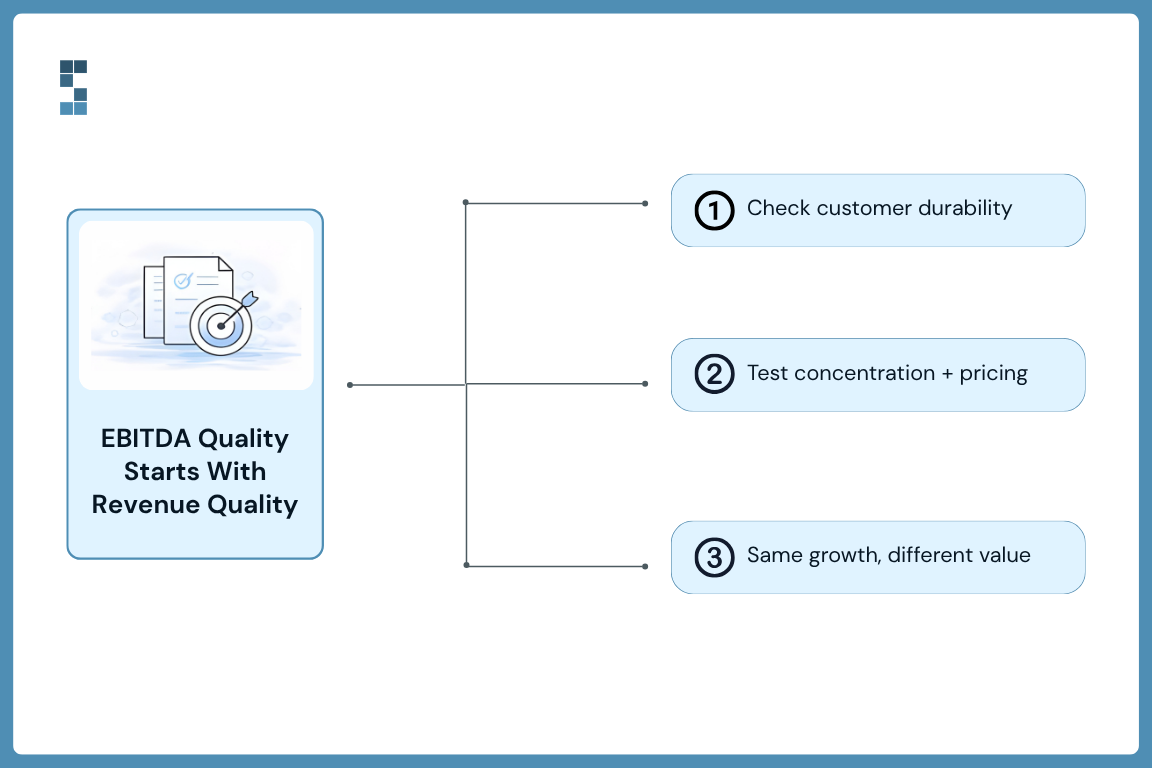
An adjusted EBITDA figure can be perfectly clean and still describe a business that is quietly falling apart. That is why adjusted EBITDA analysis has to reach below the earnings line into revenue quality.
The questions that matter: How much revenue is genuinely recurring or reliably re-occurring, versus project-based and re-won every year? What do customer cohorts look like, meaning do customers stay and grow, or is the company refilling a leaky bucket? How concentrated is the base, and what actually holds the top five accounts, contracts or the owner’s friendships? And is growth coming from volume, or from price increases that a competitor can undercut the month after close?
A company growing entirely through price on a shrinking customer base looks identical on the P&L summary to one growing through expansion on a loyal base. They deserve very different multiples. The QoE’s revenue section is what tells you which one you are buying.
Proof of cash: the credibility floor
Everything above assumes the books describe something real. Proof of cash is how you find out. The analysis ties reported revenue and earnings to actual bank activity, month by month, across the diligence period.
On unaudited, cash-basis books kept by a part-time bookkeeper, this is the single most important test in the engagement, and it is the reason I am skeptical of any cut-rate diligence product that skips it. If reported revenue cannot be traced into the bank account, there is nothing to adjust; the conversation is over. When cash ties, every schedule that follows stands on solid ground, and your lender knows it.
From findings to price: making the QoE pay for itself
A finding that never becomes a number is trivia. The last job of buy-side QoE is converting what it found into deal terms, and this is where the report earns its fee many times over.
The mechanics are straightforward. An EBITDA adjustment moves price through the multiple: at 4–7x, a $100,000 add-back that dies in diligence is $400,000 to $700,000 of purchase price. Working capital findings set the peg you negotiate, and the peg quietly moves real dollars at close. I can’t overstate this one: I have seen too many buyers get a decent business and then really struggle through a post-close cash crunch from working capital oversights. Debt-like items, including deferred revenue, unpaid payroll taxes, customer deposits, and accrued PTO, come off the price dollar for dollar. And findings you cannot quantify cleanly become escrows, holdbacks, or reps instead of price changes.
How you use the findings matters as much as the findings. Anchor every conversation on the evidence, not the accusation: this is what the schedule shows, this is the dollar impact, here is how we propose to handle it. Sellers can argue with your tone. They have a much harder time arguing with their own bank statements.
One warning from experience: do not treat the QoE as a weapon to grind price on every line. The goal is paying the right price for the real earnings, and keeping a seller relationship healthy enough to close and transition well. A buyer who retrades on every $5,000 finding kills deals that deserved to live. Save the fight for findings that move the number.
Frequently asked questions
What is a buy-side quality of earnings report?
An independent analysis, commissioned by the buyer during diligence, of whether a target’s earnings are real, recurring, and transferable. It bridges reported to adjusted EBITDA, tests add-backs, ties earnings to bank activity, and quantifies findings that affect price and terms.
How is buy-side different from sell-side QoE?
Who commissions it and whose question it answers. Sell-side is ordered by the owner to prepare and defend the numbers before going to market. Buy-side is your work product, scoped around your risks and your financing. If a sell-side report exists, use it as an input, not a substitute.
Do I need a QoE for a lower-middle-market deal if the books look clean?
Yes. Clean-looking books are an argument for a lighter scope, not for skipping diligence. Most LMM targets have never been audited, and proof of cash on a clean company is fast and cheap relative to what it protects.
What does a buy-side QoE cost?
Typically $10,000–$20,000 for a QoE Lite scope on deals under $5M, and $25,000–$50,000 for full scope from a boutique firm. See our full pricing guide for what drives the ranges.
Can I do the EBITDA analysis myself?
You should absolutely rebuild the bridge yourself; the instinct is right. But lenders and capital partners require independence, and a team that has tested hundreds of LMM add-backs will catch patterns a first-time buyer cannot. Do your own work and buy the independent version of it.
Validate the number before you pay for it
If you are under LOI or close to one, the highest-leverage thing you can do this week is get the EBITDA question moving. Send us the CIM or the seller’s P&L and we will tell you what we see in the add-backs, what scope the deal actually needs, and a fixed fee with a start date. Partner-led, built for the lower middle market, and scoped to your exclusivity window.
Book a diligence scoping call with System Six.
by Chris Williams | Sep 14, 2026 | Blog
Somewhere in almost every deal I have been part of, someone says a version of the same sentence: the company has audited financials, so we can skip the quality of earnings work. It sounds reasonable. It is also one of the more expensive misunderstandings in small-company M&A.
An audit and a QoE are not competing versions of the same product. They answer different questions, for different audiences, under different standards. I have bought companies three times now, and I would not rely on either one to do the other’s job. Here is the difference, and how to know which one your situation actually calls for.
Two different questions
An audit answers: do these historical financial statements fairly present the company’s position, in accordance with regulations? It is an opinion product. The auditor tests the statements the company prepared and issues a formal legal opinion for shareholders, regulators, and lenders. It is backward-looking by design, and it takes the business as it is, under its current owner. It is rarely used in an acquisition context.
A quality of earnings analysis answers a different question entirely: can you, the buyer, rely on these earnings to price and finance this deal? It is a decision product. Nobody issues an opinion; instead you get schedules, findings, and a bridge from reported EBITDA to what the earnings really are once owner perks, one-time items, and accounting choices are stripped out. It is forward-looking in intent, because the whole point is what transfers to you after close.
The one-line version: an audit tells you the books follow the rules. A QoE tells you whether the earnings are real, recurring, and transferable, and whether they will actually show up in Month 1 under your ownership.
Side by side
|
Quality of Earnings (QoE) |
Audit |
| Built for |
A deal decision: should you buy, based off what numbers? |
An opinion that historical statements are fairly presented in accordance with regulations |
| Core question |
Are the earnings real, recurring, and transferable to a new owner? |
Do the statements follow GAAP? |
| Commissioned by |
The buyer (or seller, pre-market), for the transaction |
The company, for shareholders, regulators, and lenders |
| Looks at |
Adjusted EBITDA, add-backs, revenue quality, working capital, debt-like items, off-statement risk |
Historical statements as presented |
| Standard applied |
Professional judgment about deal risk; no opinion issued |
GAAP audit standards; formal legal opinion issued |
| Output |
A report with findings, schedules, and quantified adjustments you negotiate with |
An opinion letter attached to the financial statements |
| Timeline |
Roughly 3–4 weeks |
Often 2–4 months |
| Typical LMM cost |
$10K–$20K (QoE Lite) to $25K–$50K (full scope) |
$20K–$75K+ annually, depending on size and complexity |
A note on reviews and compilations, since they come up in the same conversations: a review is a lighter cousin of the audit, offering limited assurance based on analytics. A compilation offers no assurance at all; the accountant simply assembles the statements. Neither one tests whether earnings survive a change of ownership, which is the question a buyer is paying to answer.
Why a clean audit can still hide a bad deal
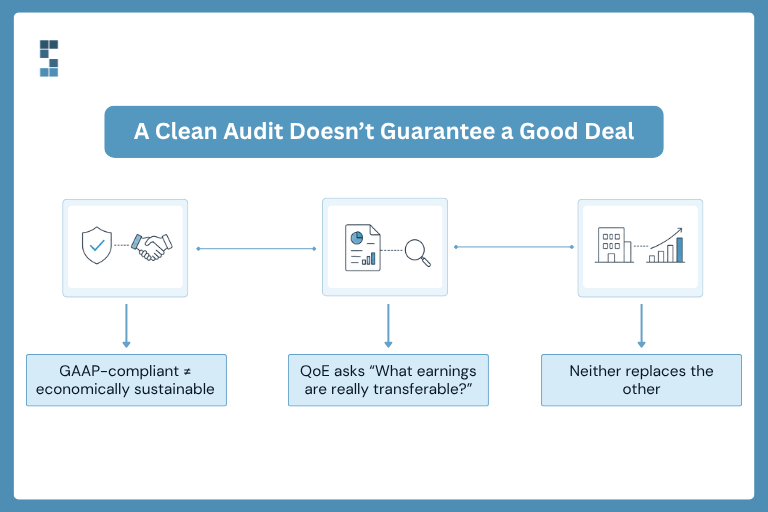
This is the part buyers most often get wrong, so let me be concrete. Audited statements can fairly present, in full compliance with GAAP, a company where 60% of revenue comes from one customer on a handshake. They can fairly present $400,000 of owner compensation booked at half the market rate for the replacement you will have to hire. They can fairly present rent paid to the seller’s own LLC at below-market rates, wages and benefits below what it will take to retain the team, and PTO accruals that simply are not on the books. Every one of those is a GAAP-clean statement and a real reduction in the earnings you are buying.
None of that is the auditor’s failure. Those things are simply not what an audit is for. The QoE exists precisely to catch what the audit is not designed to look for.
The reverse is also true, and worth saying plainly: a QoE is not a substitute for an audit either. No legal opinion is issued, and while a good QoE team will absolutely chase inconsistencies, it cannot certify compliance and it cannot catch everything. If you fundamentally do not trust your seller, no report of any kind will 100% protect you.
The lower-middle-market reality: usually there is no audit anyway
For most deals under $25M, the audit question is theoretical. The typical seller has never been audited. The books are cash-basis or loosely accrual, kept in QuickBooks by a part-time bookkeeper, and the first rigorous test those numbers ever face is your diligence.
That makes the QoE not just different from an audit but, in this market, the only independent look anyone has ever taken at the earnings. It is why lenders and equity partners insist on one. And if anyone you are working with is not insisting on it, you may want to consider how good of a partner they really are.
Which one you need, by situation
Buying a company: QoE, full stop. Whether or not audited statements exist. If the target is audited, your QoE team will happily use the audit workpapers as raw material, and the engagement often moves faster because the books are cleaner. The audit is an input to diligence, not a replacement for it.
Financing an acquisition: QoE. SBA lenders, senior lenders, and private credit funds want independent validation of the earnings that service their debt. What they almost never require for an LMM acquisition is a full audit of the target.
Running the company you already own: sometimes an audit. Post-close, an audit becomes relevant when a stakeholder requires that opinion: a bank covenant, an insurance or bonding requirement, outside investors, or an eventual exit process where audited history adds credibility.
Selling in a few years: possibly both. A sell-side QoE before going to market finds the problems while you can still fix them, and one or two years of audited or reviewed statements can strengthen a future buyer’s confidence. Which combination makes sense depends on your exit timeline and buyer universe.
Frequently asked questions
Is a QoE the same as an audit?
No. An audit issues a formal opinion on whether historical statements follow GAAP. A QoE evaluates whether earnings are real, recurring, and transferable for a transaction, and issues findings rather than an opinion.
QoE vs. audit: which do I need to buy a business?
A QoE. Lenders and investors expect independent transaction diligence, and audited statements, even when they exist, do not test the things a buyer needs tested: add-backs, revenue durability, working capital, and debt-like items.
Do audited financials make a QoE unnecessary?
No. Audited statements make the QoE faster and cheaper because the books are cleaner, but they answer a compliance question, not a deal question. A GAAP-clean company can still carry customer concentration, under-market owner comp, and off-book obligations.
Is a QoE cheaper than an audit?
Usually, yes. A lower-middle-market QoE runs $10K–$20K for a QoE Lite scope and $25K–$50K for full scope, delivered in three to four weeks. Audits are annual engagements that often cost as much or more and take months.
What about reviewed financial statements?
A review provides limited assurance that nothing obviously violates GAAP, based mostly on analytics. It sits between a compilation and an audit, and like both, it does not evaluate earnings quality for a transaction.
Talk it through with someone who has sat in your seat
If you are staring at a CIM wondering whether the seller’s audited or reviewed statements change what diligence you need, that is a fifteen-minute conversation. Bring us the deal and a partner, not an analyst pool, will tell you what the existing statements actually cover, what they don’t, and what scope fills the gap. Partner-led diligence is the whole model here. No pitch, just the map.
Talk to a QoE partner at System Six.
Page 1 of 1912345...10...»Last »